Elizabeth Regis

Activest Weekly | Week of October 5 to 9

Download the full report (PDF)

The Week in Brief

Oil and the Federal Reserve (Fed) shaped the week. Iran stepped up its attacks on tankers in the Strait of Hormuz, and a hurricane in the Gulf of Mexico forced producers to cut output, lifting Brent crude to $104.70 a barrel. On Wednesday the Fed released the minutes of its September meeting. Every official had backed that month’s rate increase, and most expect another this year.

Stocks rose anyway. The S&P 500 gained 1.0%, led by energy, consumer staples and utilities, while chipmakers fell after a Financial Times report questioned OpenAI’s revenue. Energy and defensive sectors led the week. That suggests oil prices and the Fed now set the market’s direction more than enthusiasm for artificial intelligence (AI) does.

Three Things That Mattered

The Fed is united on tightening The minutes showed no dissent over September’s increase, and most officials expect another one this year. That makes it likely borrowing costs stay high through the late-October meeting.

Oil is the inflation risk to watch Brent gained 2.4% as Gulf output was cut and tankers came under attack. Higher fuel costs feed directly into the price readings the Fed is weighing.

The chip trade lost its footing A press report casting doubt on OpenAI’s sales hit semiconductor makers hard. Leadership in American stocks moved to sectors that hold up when growth slows.

Market Dashboard

Index / Asset Level Weekly YTD
S&P 500 7,800.76 +1.0% +14.0%
Nasdaq Composite 27,346.62 +0.6% +17.7%
Dow Jones Industrial Avg. 51,456.94 +0.5% +7.1%
Russell 2000 2,801.24 -1.1% +12.9%
Nikkei 225 JPY 69,030.92 +1.1% +37.1%
STOXX Europe 600 EUR 631.49 +0.0% +6.5%
Hang Seng HKD 24,211.35 +1.0% -5.5%
U.S. 10-Yr Treasury Yield 5.27 0 bps +111 bps
Brent Crude 104.70 +2.4% +72.1%
Gold 4,207.30 +1.1% -3.1%
VIX 14.98 -0.33 +0.03

Weekly and YTD are price returns and exclude dividends. All figures are index and asset returns, not the performance of any strategy or client account. Yields in basis points, VIX in index points. Levels and returns in US dollars unless the row is marked with another currency; international indices are quoted in their own currency, so a US dollar result will differ with exchange-rate moves. Levels as at 11:00 AM New York, Friday, October 9, 2026; changes for markets still open then are not final, and closed markets are at their close. A dash means the figure could not be verified. Source: exchange and index-provider data; Cboe for Treasury yields.

United States: Economy & Policy

A unanimous Fed leans toward another increase The minutes of the Federal Open Market Committee (FOMC) meeting held in mid-September came out Wednesday. They show that every official supported the quarter-point increase that set the fed funds target range at 3.75% to 4.00%, the Fed’s first increase in three years. Most officials judged that another rise would likely be needed this year. Many described financial conditions, including rising stock prices, as supportive of growth, which makes the equity rally part of the case for tightening. The committee meets next on October 27 and 28.

Oil puts inflation back on the agenda The latest Consumer Price Index (CPI), for August, showed prices up 3.4% from a year earlier, according to the Bureau of Labor Statistics. The core measure, which excludes food and energy, rose 2.4%. Energy accounts for much of that gap, and the war with Iran, now in its eighth month, added to it this week through tanker attacks, as did a Gulf hurricane. The September CPI arrives Wednesday. If fuel costs show up in core prices, the case for another increase gets stronger; a steady core would weaken it.

Households grow gloomier The University of Michigan’s preliminary October survey, released Friday, showed consumer sentiment at its lowest since May, with high prices weighing on households. Hiring has slowed as well: according to the Bureau of Labor Statistics, payrolls grew by just 29,000 in September and the unemployment rate rose to 4.2%. Retail spending was still strong in August. Thursday’s September retail sales figures will show whether weaker confidence has started to reach the checkout.

Markets & Earnings

Energy and defensives lead Within the S&P 500, energy shares climbed 4.6% as crude rose. Consumer staples and utilities were close behind, sectors that typically hold up when growth and rates look uncertain. Smaller companies did worse. The Russell 2000, whose members rely more on floating-rate debt, fell 1.1%, a reminder of what higher-for-longer rates cost businesses that borrow heavily.

A revenue report hits chipmakers On Thursday the Financial Times reported that OpenAI’s revenue was lower than previously estimated, and makers of chips sold into AI data centers fell. Intel was already under pressure from Monday, when Elon Musk confirmed talks about Taiwan Semiconductor joining Terafab, his Texas chip venture. Intel fell 10.7% on the week, and technology was the weakest sector in the S&P 500.

Deals behind the biggest gains

PTC rose 35.0%, the largest gain in the S&P 500, after Schneider Electric agreed to buy the industrial software maker in an all-cash deal.

Constellation Energy rose 14.5% after signing a 20-year agreement to supply Google with nuclear power, the latest sign of AI data centers seeking long-term electricity contracts.

Crown Castle gained 16.4%. SpaceX agreed to buy a nationwide block of low-band spectrum, a move Bernstein said keeps alive the possibility that SpaceX builds a ground network, which would need towers. SBA Communications rose with it.

The Bottom Line. This week’s equity gains came from energy and defensive sectors, while the Fed signaled that more tightening is likely, so the rate pressure on portfolios has not eased. Wednesday’s September CPI is the next test. A firm core reading would strengthen the case for an October increase; a softer one would relieve bonds and technology shares.

International

Japan The Nikkei 225 rose 1.1% on the week, and the dollar ended at 158.42 yen. A weak yen raises the yen value of exporters’ overseas earnings. Japan imports most of its energy, though, so expensive crude cuts into that benefit.

Europe The STOXX Europe 600 ended the week flat, and the euro slipped against the dollar. Like the U.S., Europe faces inflation pressure from oil. The European Central Bank (ECB) next sets rates on October 29.

Hong Kong The Hang Seng rose 1.0% in a week when mainland Chinese markets reopened after the Golden Week holiday. Even so, the index is still 5.5% lower this year, well behind the gains in Tokyo.

Commodities

Brent crude up 2.4% Iran stepped up attacks on tankers just as traffic through Hormuz neared prewar levels. Hurricane Isaias led Shell, Chevron and others to cut Gulf of Mexico output. The International Energy Agency (IEA) agreed to speed up releases from emergency stocks, prioritizing diesel. On Thursday, President Trump said the U.S. would not attack Iran before the midterm elections.

Copper and gold higher Copper rose 3.2% as Chinese buyers returned after the national holiday. Gold gained 1.1% while silver fell, so the two precious metals went in opposite directions despite the same backdrop of high yields and a firmer dollar.

The Week Ahead

  • Monday, Oct 12. U.S. bond markets are closed for Columbus Day; stock markets are open.
  • Tuesday, Oct 13. JPMorgan Chase reports third-quarter results before the open.
  • Wednesday, Oct 14. Consumer Price Index for September. The Federal Reserve releases its Beige Book.
  • Thursday, Oct 15. Retail sales for September. Producer Price Index for September. Federal Reserve Chairman Kevin Warsh in conversation with International Monetary Fund (IMF) Managing Director Kristalina Georgieva.
  • Friday, Oct 16. Industrial production and capacity utilization for September. Import and export prices.

Activest Wealth Management, LLC is an investment adviser registered with the U.S. Securities and Exchange Commission; registration does not imply a certain level of skill or training. This material is provided for informational purposes only and does not constitute investment, legal or tax advice, an offer to buy or sell securities, or a solicitation of any offer. Information herein is drawn from sources believed to be reliable, but its accuracy and completeness are not guaranteed. Views are as of the date of publication and subject to change without notice. Index returns do not reflect the deduction of advisory fees or expenses, and you cannot invest directly in an index. Past performance is no guarantee of future results. All investments involve risk, including possible loss of principal. Please refer to Activest Wealth Management, LLC’s Form ADV Part 2 for additional information and risks. All market data as of the close on the date shown unless otherwise noted.
Brazil Heads to a Presidential Runoff

Senator Flávio Bolsonaro finished narrowly ahead of President Lula in the first round. The two meet again on October 25, and Brazilian markets have already reacted.

What the first round showed

Brazil’s presidential election will be decided in a runoff on October 25. In the first round on October 4, Senator Flávio Bolsonaro of the Liberal Party (PL), a son of former President Jair Bolsonaro, received 47.03% of valid votes. President Luiz Inácio Lula da Silva of the Workers’ Party (PT) received 45.16%. The campaign focused on the cost of living, corruption and public safety, Reuters reported. Abstention, at 21.08%, was the highest since 1998. Starting next year, the PL will hold more seats than any other party in both the Senate (28 of 81) and the Chamber of Deputies (121 of 513), according to Americas Quarterly.

The result differed from most pre-election polls. Datafolha’s final survey, taken the day before the vote, had Lula ahead 45% to 42% among valid votes. Prediction markets moved after the count. On October 7, Polymarket priced Bolsonaro’s chance of winning the runoff at about 85%, up from roughly 60% before the vote, according to The Rio Times. Kalshi, a US exchange regulated by the CFTC, showed a similar level. These prices reflect traders’ bets, not polls, and can change quickly. The first runoff polls are due on October 8.

Brazilian assets moved sharply on the result. On October 5, the Ibovespa stock index rose 7.7% to 206,912 points, its largest one-day gain since March 2020, and the real gained about 4% against the US dollar, Reuters reported. Investors read the outcome as improving the chances of a more fiscally conservative government. Analysts also pointed to limits. Andrés Abadía of Pantheon Macroeconomics noted that whoever wins will face rising mandatory spending and high debt-service costs. Alessandra Ribeiro of Tendências Consultoria told Americas Quarterly that the risk of disappointment on fiscal adjustment is significant. Brazil’s public debt is above 82% of GDP.

The three weeks before the runoff leave room for change. The União Brasil–Progressistas federation, which won 87 lower-house seats, has endorsed Bolsonaro, as have eliminated candidates Ronaldo Caiado and Romeu Zema. The PSD stayed neutral. Lula is focusing on his base in the Northeast and on voters who stayed home. Endorsements do not transfer votes automatically, and about 9.3 million votes went to other candidates. In the 2022 runoff, the closest in Brazil’s history, Lula won with 50.9% to 49.1%. The winner will lead Brazil from January 2027.


Activest Wealth Management, LLC is an investment adviser registered with the U.S. Securities and Exchange Commission; registration does not imply a certain level of skill or training. This material is provided for informational purposes only and does not constitute investment, legal or tax advice, an offer to buy or sell securities, or a solicitation of any offer. Information herein is drawn from sources believed to be reliable, but its accuracy and completeness are not guaranteed. Views are as of the date of publication and subject to change without notice. Index returns do not reflect the deduction of advisory fees or expenses, and you cannot invest directly in an index. Past performance is no guarantee of future results. All investments involve risk, including possible loss of principal. Please refer to Activest Wealth Management, LLC’s Form ADV Part 2 for additional information and risks. All market data as of the close on the date shown unless otherwise noted.
What Trump Accounts Mean for Families With Children

Every eligible American child now has a Trump Account. For families already using 529 plans, custodial accounts and regular gifts, the question is how it fits.

A new account for children and grandchildren under eighteen

The Treasury has finished automatically enrolling eligible children in Trump Accounts, so in many families every child and grandchild under eighteen now has one. The accounts cover every eligible child under the age of eighteen with a valid Social Security number, the Treasury said. Each is a tax-advantaged investment account, and like any investment account its value can rise or fall. Family members, friends and employers can contribute only once a parent or guardian claims the account. Claiming matters most for the youngest children. Certain children born from 2025 through 2028 can receive a one-time $1,000 seed contribution from the Treasury, and it is paid only into accounts that have been claimed.

For families that already plan for the next generation, a Trump Account adds to what is in place; it does not replace it. Federal law created it as a type of traditional individual retirement account for a child, so it is built for the long term. A 529 plan, by contrast, is built around education. A custodial account is different again: gifts to it belong to the child and typically pass to the child’s control as a young adult. For grandparents who make regular gifts to grandchildren, a contribution here is one more gift to weigh alongside those already planned. Families that own a business face an open question, because the rules for employer contributions to these accounts are still a proposal awaiting a public hearing.

Before claiming an account or adding money to it, a few points are worth settling within the family. The first is who claims it, since the person who claims an account manages it. A parent or guardian can claim, and IRS rules also allow a legal custodian to do so. The second is how each account fits the plan for that particular child, since every eligible child has an account of their own. The third is timing: parts of the rules are still open for public comment, so details may change. Claiming an account does not commit anyone to contribute. Whether it deserves new money is a separate decision, best made alongside the family’s 529 plans, custodial accounts and gifting plan.


Activest Wealth Management, LLC is an investment adviser registered with the U.S. Securities and Exchange Commission; registration does not imply a certain level of skill or training. This material is provided for informational purposes only and does not constitute investment, legal or tax advice, an offer to buy or sell securities, or a solicitation of any offer. Information herein is drawn from sources believed to be reliable, but its accuracy and completeness are not guaranteed. Views are as of the date of publication and subject to change without notice. Index returns do not reflect the deduction of advisory fees or expenses, and you cannot invest directly in an index. Past performance is no guarantee of future results. All investments involve risk, including possible loss of principal. Please refer to Activest Wealth Management, LLC’s Form ADV Part 2 for additional information and risks. All market data as of the close on the date shown unless otherwise noted.
Activest Weekly | Week of September 21 to 25

Download the full report (PDF)

The Week in Brief

The Federal Reserve’s stance on inflation drove the week. Governor Michael Barr said further rate increases are likely to be needed, a business survey showed U.S. activity accelerating, and Brent crude rose with the Strait of Hormuz still closed. All of it came a week after the Fed’s first rate increase since 2023. The 10-year Treasury yield climbed to 5.21%, its highest level since 2007.

Rising rates split the markets. The S&P 500 rose 0.9% on a rally in technology shares, while utilities and corporate bonds fell and the Mexican peso lost ground sharply against the dollar. For portfolios, tighter policy is costing most in bonds and rate-sensitive shares. August inflation data on Wednesday and the September jobs report on Friday will show whether that pressure builds.

Three Things That Mattered

The Fed is signaling more increases Barr’s remarks, a week after the first increase since 2023, point to further tightening. That keeps bond prices under pressure until inflation data show energy costs are contained.

Income assets bore the cost Utilities fell 4.5%, and corporate and long-dated government bonds had unusually weak weeks. Assets valued for their income are being repriced as yields climb.

Oil keeps inflation risk alive Brent rose with the Strait of Hormuz closed, keeping up the energy costs behind headline inflation. The reported talks on reopening the strait bear most directly on that pressure.

Market Dashboard

Index / Asset Level Weekly YTD
S&P 500 7,717.73 +0.9% +12.7%
Nasdaq Composite 26,995.70 +1.8% +16.2%
Dow Jones Industrial Avg. 51,504.66 -0.3% +7.2%
Russell 2000 2,827.94 -1.1% +13.9%
Nikkei 225 JPY 66,364.20 +2.1% +31.8%
STOXX Europe 600 EUR 638.48 +0.5% +7.7%
Hang Seng HKD 24,510.09 -1.0% -4.4%
U.S. 10-Yr Treasury Yield 5.21 +22 bps +105 bps
Brent Crude 106.04 +2.1% +74.3%
Gold 4,314.10 -2.5% -0.6%
VIX 15.54 +0.73 +0.59

Weekly and YTD are price returns and exclude dividends. All figures are index and asset returns, not the performance of any strategy or client account. Yields in basis points, VIX in index points. Levels and returns in US dollars unless the row is marked with another currency; international indices are quoted in their own currency, so a US dollar result will differ with exchange-rate moves. Levels as at 11:00 AM New York, Friday, September 25, 2026; changes for markets still open then are not final, and closed markets are at their close. A dash means the figure could not be verified. Source: exchange and index-provider data; Cboe for Treasury yields.

United States: Economy & Policy

Barr makes the case for more increases Federal Reserve Governor Michael Barr said on Wednesday that further rate increases are "likely to be needed." His argument was that risks to the inflation target have grown while those to the labor market have receded. He spoke a week after the Fed lifted the fed funds target range to 3.75% to 4.00%, its first increase since 2023, and traders added to bets on another move in October. For bondholders, the question is now how far the Fed tightens. The next test is Wednesday’s August reading of personal consumption expenditures (PCE) inflation, the Fed’s preferred gauge.

A survey shows an economy running hot The purchasing managers’ index (PMI) is a monthly survey of business activity. S&P Global’s flash reading for September put U.S. composite output at 58.4, its highest in 54 months. Analysts cited that strength, along with Barr’s remarks and energy costs, among the reasons yields rose. Firm activity combined with expensive energy is what keeps the Fed leaning toward tightening. The labor market offers no counterweight yet: unemployment held steady in the August employment report, published earlier this month. The September report arrives on Friday.

Energy keeps headline inflation elevated The latest inflation figures came out before this week, but they shape its debate. According to the Bureau of Labor Statistics, consumer prices rose 3.4% in the year to August. Core prices, which exclude food and energy, rose 2.4%. That gap points to energy as the main source of pressure while the Strait of Hormuz stays closed. The concern Barr voiced is that the energy shock spreads into broader prices. Wednesday’s PCE release is the next reading on whether that is happening.

Markets & Earnings

Technology carried the S&P 500 The S&P 500 rose 0.9%, lifted almost entirely by technology. The index’s technology sector gained 3.5% as chipmakers rallied and software and data companies announced artificial-intelligence contracts and upbeat forecasts. That leaves the index’s gains resting on one theme, and Micron’s results on Wednesday are its next test.

Rate-sensitive shares gave ground Utilities, which compete with bonds for investors seeking income, fell 4.5% as yields climbed, an unusually steep week for the sector. The Russell 2000 of smaller companies fell 1.1%. Energy shares fell even as crude rose, with the refiner Valero among the S&P 500’s heaviest decliners.

Corporate bonds felt the rate move Measured against their own history, investment-grade corporate bonds suffered an unusually large weekly decline as Treasury yields rose. For balanced portfolios, higher rates are costing most in the holdings meant to provide stability. The same rise in yields also lifts the income available on new bond purchases.

Company news behind the biggest moves

Moderna rose 26.8%, the S&P 500’s largest gain, extending a rally that began with late-stage melanoma results in August for its Merck-partnered cancer vaccine.

Gen Digital, owner of Norton, fell 22.7%, the S&P 500’s steepest decline, in the week the Financial Times reported it had approached GoDaddy about a takeover.

Two gainers rose on forward-looking news. Everpure set out a preliminary fiscal 2028 outlook, and Akamai Technologies announced a seven-year cloud-services agreement with Anthropic.

The Bottom Line. Tighter policy is hitting bond holdings and rate-sensitive shares first, while technology shares are carrying equity returns. A reopened Strait of Hormuz or softer August inflation data would ease the pressure on rates; firmer readings would add to it.

International

Tokyo climbs, Hong Kong slips The Nikkei 225 rose 2.1% as the yen weakened against the dollar, adding to a strong year for Japanese shares. Hong Kong went the other way. The Hang Seng fell 1.0% and remains lower for the year, apart from the gains elsewhere in Asia’s largest markets.

Europe steadier than its bonds The STOXX Europe 600 added 0.5%. S&P Global’s flash surveys showed euro-area output growing at its fastest pace in nearly three and a half years. The euro and the pound both weakened against the dollar, and Britain’s survey showed price pressures intensifying.

The peso takes the sharpest hit The dollar rose 3.3% against the Mexican peso, far outside the pair’s usual weekly range. Banco de México left its benchmark rate unchanged on Thursday, as economists had expected. The slide came as U.S. yields climbed, which narrows the peso’s interest-rate advantage over the dollar.

Commodities

Oil stays high with Hormuz shut Brent crude rose 2.1% to $106.04 a barrel. The Strait of Hormuz, the route for about a fifth of the world’s oil and liquefied natural gas, remains closed during the U.S.-Israeli war with Iran. Late in the week, The Wall Street Journal reported that American and Iranian negotiators were working toward reopening it.

Gold slips as yields rise Gold fell 2.5% to $4,314.10 an ounce. Higher Treasury yields and a firmer dollar raised the cost of holding a metal that pays no income, and expectations of further Fed increases added to the pressure. Silver fell as well.

The Week Ahead

  • Tuesday, Sep 29. The Bureau of Labor Statistics publishes its August Job Openings and Labor Turnover Survey.
  • Wednesday, Sep 30. The Bureau of Economic Analysis releases August personal income and spending, including PCE inflation, along with its gross domestic product report. Micron Technology reports quarterly results after the close.
  • Thursday, Oct 1. The Labor Department publishes weekly jobless claims, and the Census Bureau releases August construction spending.
  • Friday, Oct 2. The Bureau of Labor Statistics releases the September employment report.

Activest Wealth Management, LLC is an investment adviser registered with the U.S. Securities and Exchange Commission; registration does not imply a certain level of skill or training. This material is provided for informational purposes only and does not constitute investment, legal or tax advice, an offer to buy or sell securities, or a solicitation of any offer. Information herein is drawn from sources believed to be reliable, but its accuracy and completeness are not guaranteed. Views are as of the date of publication and subject to change without notice. Index returns do not reflect the deduction of advisory fees or expenses, and you cannot invest directly in an index. Past performance is no guarantee of future results. All investments involve risk, including possible loss of principal. Please refer to Activest Wealth Management, LLC’s Form ADV Part 2 for additional information and risks. All market data as of the close on the date shown unless otherwise noted.
Two Strategies Are Shaping the Future of AI

The U.S. bets on advanced models, while China focuses on industrial applications. The AI race is advancing through distinct strategies and global opportunities.

Two Paths to Leadership in Artificial Intelligence

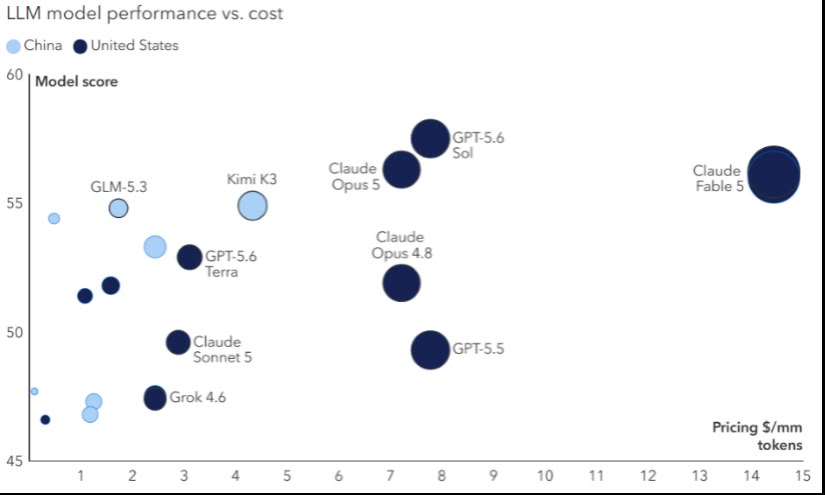
The U.S. and China are advancing artificial intelligence through different approaches. U.S. companies are investing heavily in increasingly advanced models, while China prioritizes efficient, lower-cost industrial applications such as robotics and autonomous driving. Rather than producing a single winner, both ecosystems could coexist and serve different market needs.

Competition could accelerate innovation, but it may also create volatility and shifts in market leadership. For investors, opportunities could extend beyond model developers to semiconductors, infrastructure, cloud computing, robotics, and companies that use AI to improve productivity.

Tokenomics: China’s AI models lead on cost

Source: Capital Group

Weekly Global Outlook

Week of September 14–18 

The Fed raises rates again as central banks adjust their strategies amid mixed economic signals. 

Markets are navigating high interest rates, persistent inflation, and diverging economic signals. While the Fed resumed rate hikes, other economies are adjusting monetary policy to address different growth challenges. 

United States 

  • The Fed raised rates by 25 bps to 3.75%–4.00% as inflation remained elevated. Updated projections point to the possibility of another rate hike this year. 

Europe 

  • The Bank of England held rates at 3.75% in a split decision, despite inflation accelerating to 3.1% in August. In Germany, the IMK raised its 2026 growth forecast from 0.6% to 1.3%, supported by stronger exports and increased government spending on defense and infrastructure. 

Japan 

  • The Bank of Japan raised rates to 1%, a 31-year high, while industrial production rose 3.9% year over year in July despite a 0.2% monthly decline. 

China 

  • Activity showed mixed signals: retail sales rose just 0.4% year over year and fixed-asset investment fell 7.2%, while industrial production grew 5.2%. 

Brazil 

  • The central bank cut the Selic rate by 25 bps to 13.75%, its fifth consecutive reduction, amid clearer signs of an economic slowdown. 

Mexico 

  • Industrial activity rose 2.4% year over year in July, its strongest performance since October 2023, driven by construction and a recovery in manufacturing. 

“You can lose money very fast, in two months, but you very rarely make money very fast in the stock market.” 

— Peter Lynch 

Upcoming Events 

  • In the United States, several labor market indicators will be released — 09/24 
  • In the United States, new home sales data will be released — 09/24 

Market Monitor 

Panorama global semanal 

Semana del 14 al 18 de septiembre 

La Fed vuelve a subir tasas, mientras los bancos centrales ajustan su estrategia ante señales económicas mixtas. 

Los mercados navegan un entorno de tasas elevadas, inflación persistente y señales económicas divergentes. Mientras la Fed retomó las alzas, otras economías ajustan su política monetaria ante distintos retos de crecimiento. 

Estados Unidos 

  • La Fed elevó la tasa en 25 pb, a 3.75%–4.00%, ante una inflación aún elevada. Los nuevos pronósticos apuntan a la posibilidad de un incremento adicional este año. 

Europa 

  • El Banco de Inglaterra mantuvo la tasa en 3.75% en una decisión dividida, pese a que la inflación se aceleró a 3.1% en agosto. En Alemania, el instituto de política macroeconómica (IMK) elevó su previsión de crecimiento para 2026 de 0.6% a 1.3%, apoyado por mejores exportaciones y un mayor gasto público en defensa e infraestructura. 

Japón 

  • El Banco de Japón elevó su tasa a 1%, máximo en 31 años, mientras la producción industrial creció 3.9% anual en julio, aunque retrocedió 0.2% mensual. 

China 

  • La actividad mostró señales mixtas: las ventas minoristas crecieron apenas 0.4% anual y la inversión fija cayó 7.2%, mientras la producción industrial avanzó 5.2%. 

Brasil 

  • El Banco Central redujo la Selic en 25 pb, a 13.75%, su quinto recorte consecutivo, ante señales más claras de desaceleración económica. 

México 

  • La actividad industrial creció 2.4% anual en julio, su mejor desempeño desde octubre de 2023, impulsada por la construcción y la recuperación manufacturera.

“You can lose money very fast, in two months, but you very rarely make money very fast in the stock market.” 

— Peter Lynch 

Próximos eventos clave 

  • En Estados Unidos, se darán a conocer datos relacionados con el empleo — 09/24 
  • En Estados Unidos, se dará a conocer el dato de ventas de nuevas casas — 09/24 

Monitor: 

The Fed Takes a Firmer Stance on Inflation

The Fed raised rates by 25 bps and signaled another increase could come this year. Persistent inflation pushes the Fed toward tighter monetary policy.

The Fed Resumes Its Rate-Hike Cycle

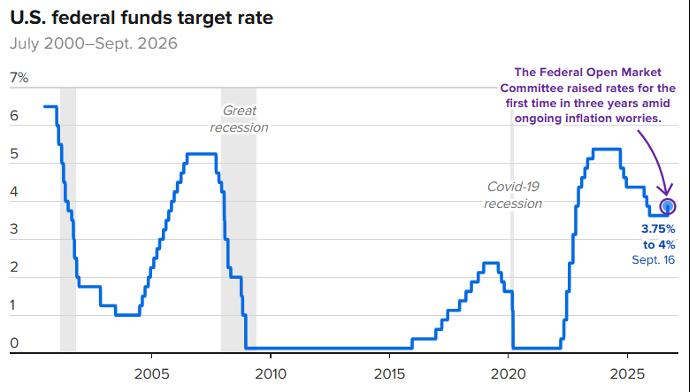
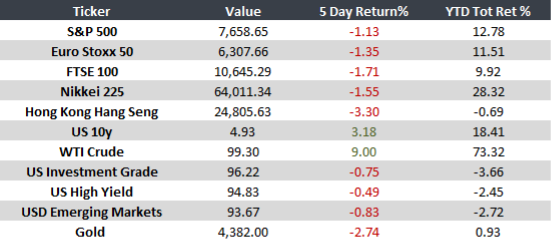
The Fed raised its policy rate by 25 basis points to a range of 3.75%-4.00%, its first increase since 2023. The unanimous decision reflects inflation that remains above target, pressured by higher energy costs and other factors. Updated projections point to the possibility of another increase this year, while the economy and labor market remain resilient.

The return of rate hikes confirms that price stability remains the Fed’s priority. Higher rates for longer could pressure valuations and raise borrowing costs, but they also offer higher yields in fixed income. In this environment, maintaining diversification and investment discipline becomes increasingly important.

Monitor

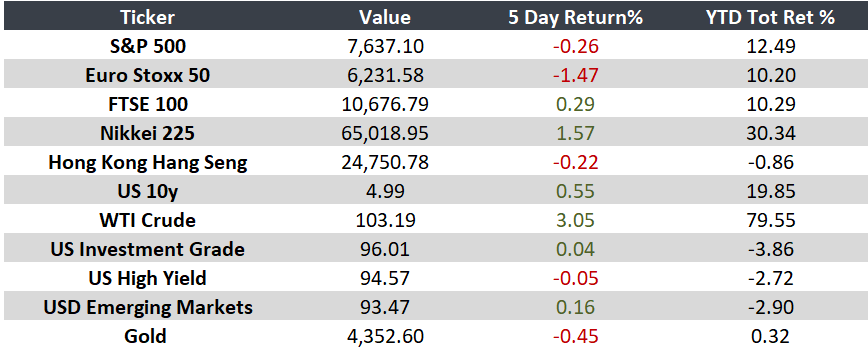
Source: Federal Reserve Bank of New York

Weekly Global Outlook 

Persistent inflation, higher interest rates, and mixed signals for global growth. 

Inflation returned to the forefront of market attention. The Fed and ECB face greater pressure on interest rates, while Asia shows mixed signals and Latin America continues to see a gradual easing in price pressures. 

  • United States: Annual inflation stood at 3.4% in August, while PPI reached 5.4%. Markets raised the probability of a Fed rate hike in September to 87% amid greater energy-related price pressures. 

  • Europe: The ECB raised its policy rate to 2.50% amid 3.3% inflation and heightened energy risks. In Germany, inflation rose to 2.9%, while exports declined in July. 

  • Japan: The economy grew at a 1.4% annualized rate in Q2 2026, supported by government spending and exports. Producer prices rose 7.6% year over year, reflecting persistent energy and raw material cost pressures. 

  • China: Exports rose 25% year over year in August, supported by technology and AI-related demand. Consumer inflation increased to 0.8%, while producer prices rose 3.8% amid higher energy costs. 

  • Argentina: Annual inflation eased to 33.7% in August, with prices rising 1.7% month over month, down from 2.1% in July. Year-to-date inflation reached 21.3%. 

  • Brazil: Annual inflation eased to 4.22% in August, while consumer prices fell 0.32% month over month, supported by softer price pressures in transportation and housing. 

  • Mexico: Inflation stood at 3.26% year over year in August. The Ministry of Finance projects a fiscal deficit of 3.9% of GDP and growth of 1.5%–2.5% in 2027, while auto production fell 1.4% year over year. 

“Time is your friend, impulse is your enemy.” 
— John Bogle 

Upcoming Events 

  • In the United States, retail sales data will be released — 09/16 
  • In the United States, the FED’s monetary policy decision will be announced — 09/16 

Market Monitor 

Indicative prices as of 10:00 AM EST 

Rates

Rates are normalizing and reshaping opportunities for investors. Higher rates are shifting the balance between growth, income, and risk. 

A New Environment for Stocks and Bonds 

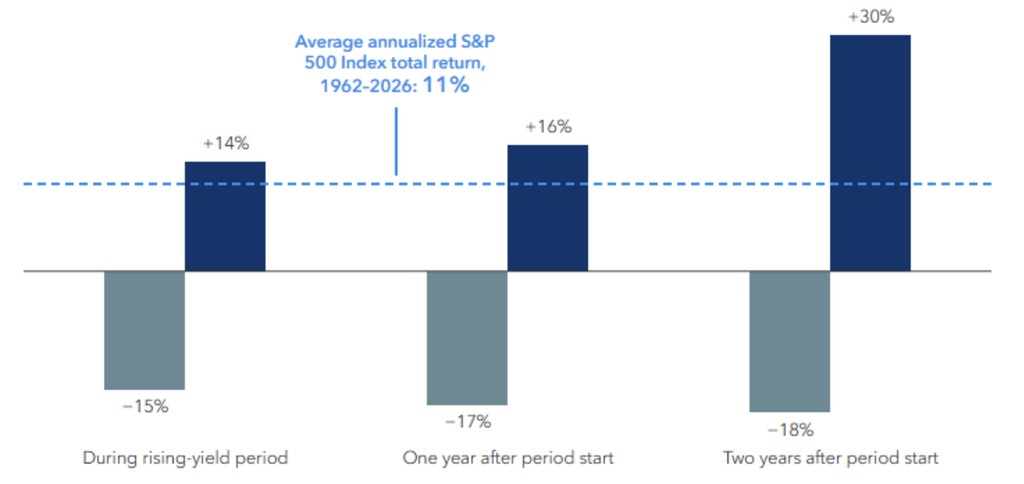
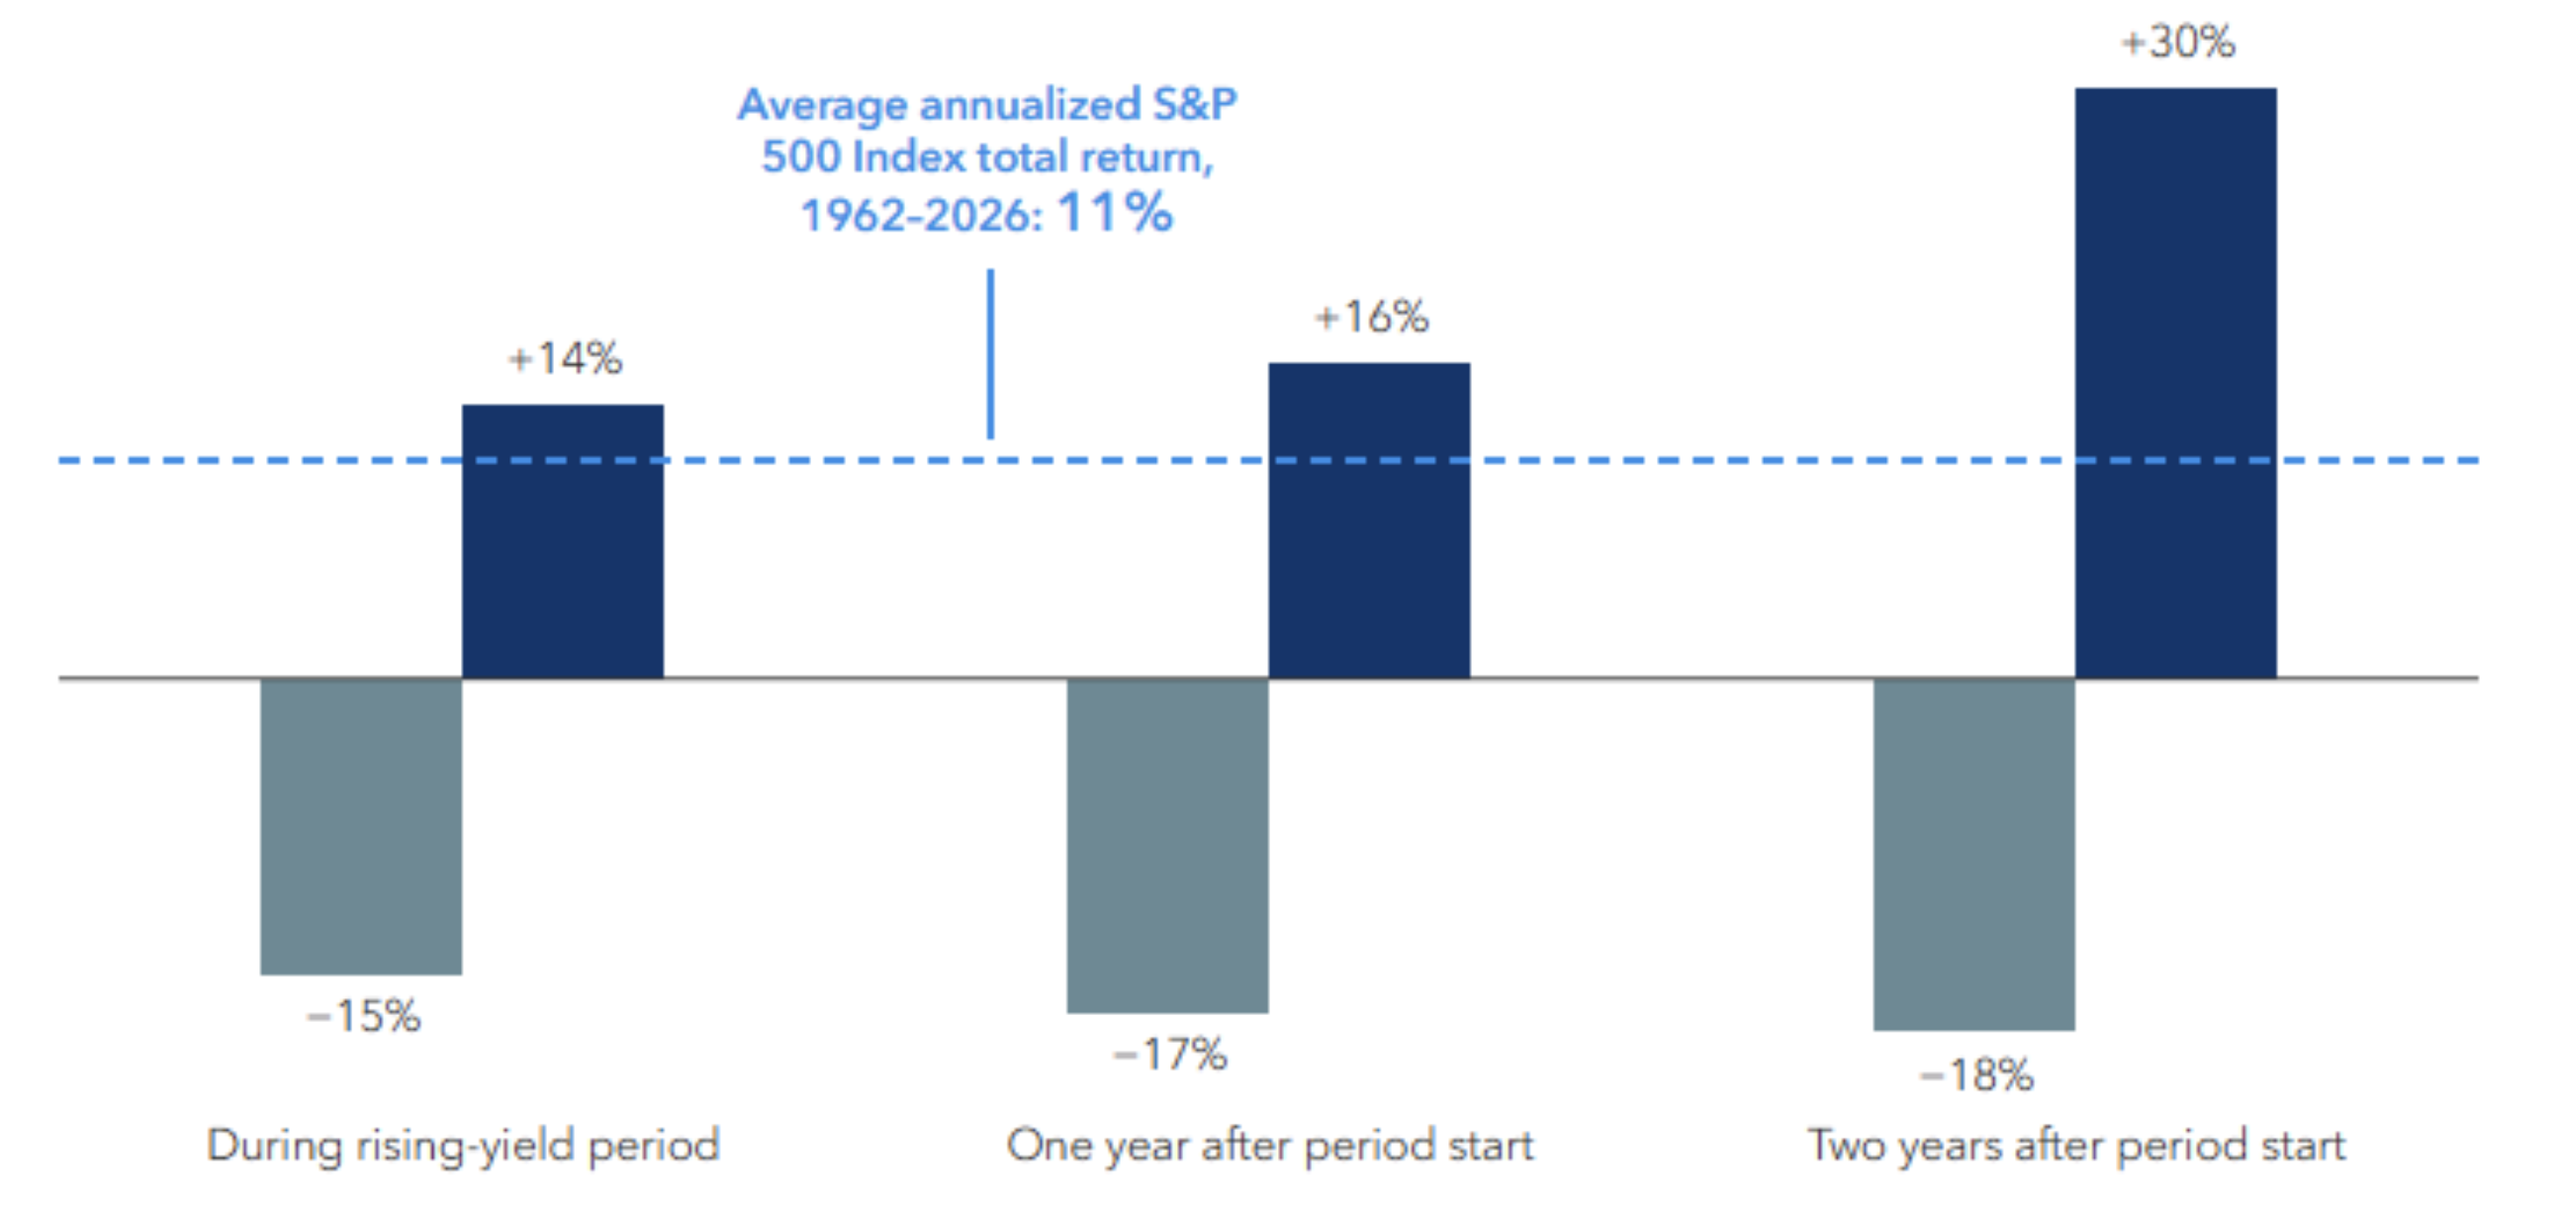
U.S. Treasury yields have risen amid a resilient economy, persistent inflation, and higher government debt. Although higher rates often generate volatility, they have historically not prevented stocks from performing well when accompanied by economic growth. At the same time, yields near 5% are making bonds more attractive as a source of income and diversification. 

This environment calls for greater selectivity. In equities, higher rates can pressure valuations of high-growth companies, favoring diversification into sectors with strong cash flows. In fixed income, higher starting yields improve income and downside protection potential, reinforcing bonds’ role as a counterbalance to equity volatility. 

Monitor

Source: Capital Group

Ponte en contacto con nosotros

Receive the best financial market news

Cookie Policy

We use our own and third party cookies to improve our services and show you advertising related to your preferences, by analyzing your browsing habits. By continuing, you confirm that you have read and accept this policy.