Jacobo Taurel

A divided Fed: what’s next for the markets?

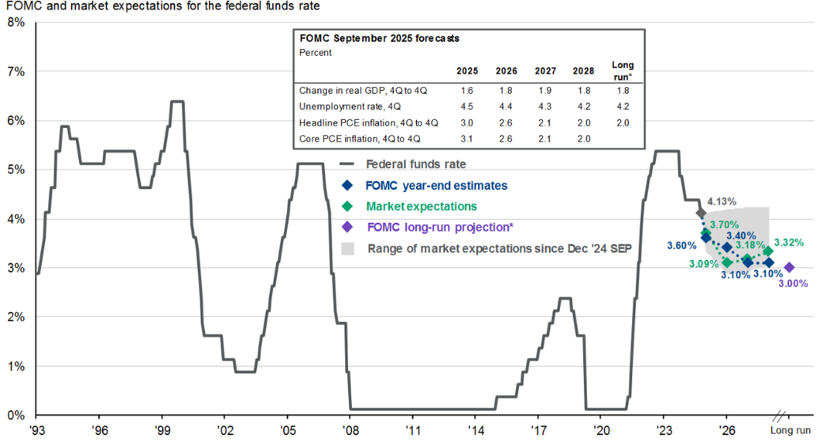
The Federal Reserve has not reached a clear agreement on its next steps. 

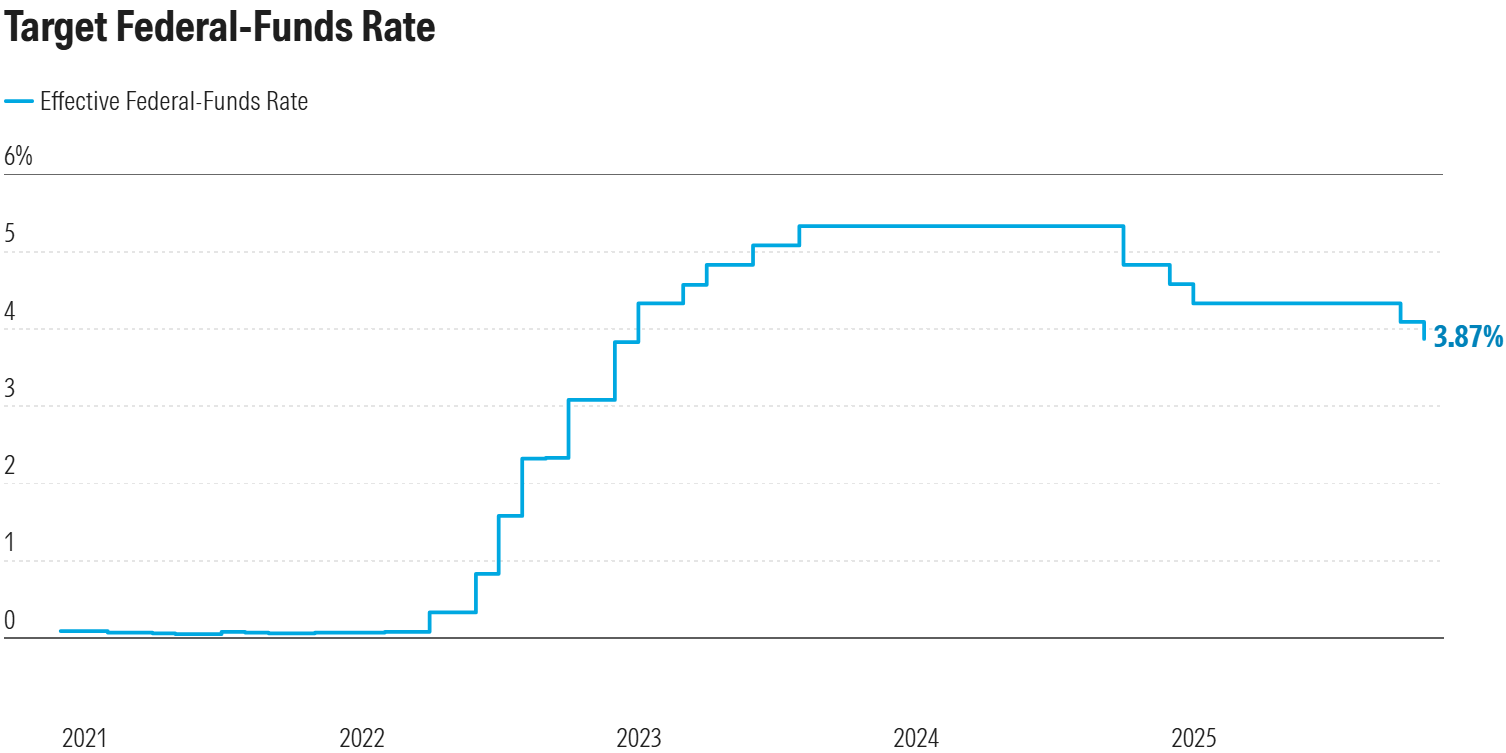
A few weeks ago, the Fed cut its rate by 25 bps, but the real surprise came from the vote: one member called for a deeper cut, while another preferred none at all. 
Two opposing positions that reveal an important fact: the economy is sending mixed signals. 

In this scenario, Jerome Powell was clear: a December cut is not guaranteed. 
Rather than dysfunction, this division shows that the path ahead remains uncertain. 
Why is the Fed divided? Because economic data continue to send conflicting and inconsistent signals. 

Key points: 
☑ Stock market at record highs 
☑ Accelerating investment in AI 
☑ Resilient consumer spending 
☑ Labor market losing momentum 
☑ Housing sector stagnating 
☑ Rising layoffs and credit card delinquencies 
☑ Government shutdown delaying key data, reducing visibility for both the Fed and the markets 

A divided Fed doesn’t imply chaos, but rather caution in the face of an ambiguous economy and incomplete data. 

The message for investors is clear: it’s not about predicting the next move, but about staying disciplined and focused on long-term horizons. 
Source: Morningstar 
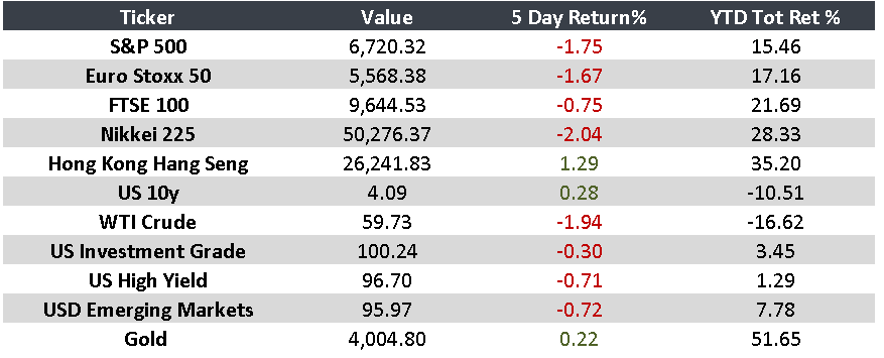
Week of stable rates and mixed signals in manufacturing

Markets reflected a week of steady interest rates, weaker manufacturing data, and resilience in services. In the United States, the government shutdown remains unresolved, while year-end spending shows a more moderate tone compared with 2024. 

United States: 
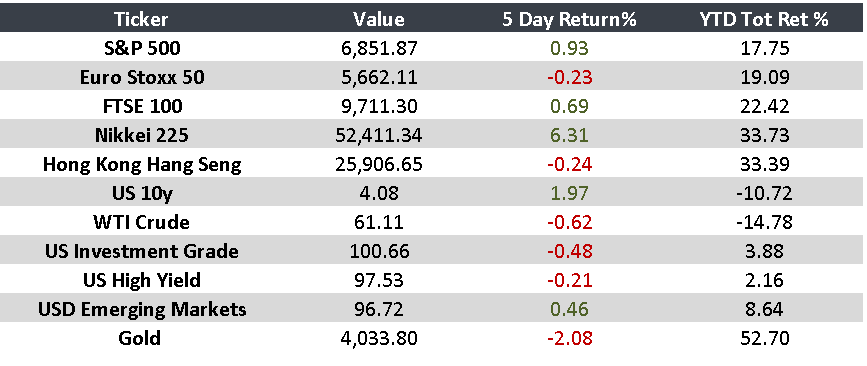
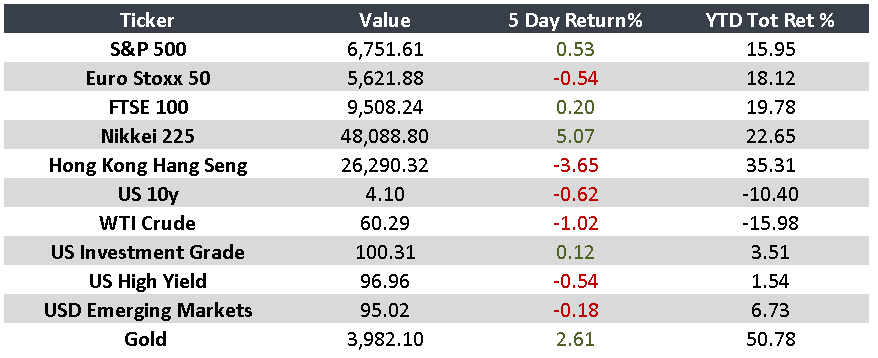
Concerns over AI valuations drove market sentiment. Manufacturing activity declined, but the services sector rebounded. The government shutdown set a new record, and year-end spending is expected to moderate. 

Europe: 
Eurozone manufacturing stalled due to a lack of new orders, although production continued to grow. The Bank of England kept its policy rate at 4%, as expected. 

Asia: 
In Japan, manufacturing posted its worst reading in more than a year, pressured by weak demand in autos and semiconductors. The services sector remained resilient despite a slower pace of new orders. 
In China, manufacturing activity fell to its lowest level in six months. Services expanded but at the slowest pace since July, mainly due to weaker export demand. 

Latin America: 
In Brazil, the Central Bank held its key rate at 15%, the highest level since 2006, indicating caution amid persistent inflationary pressures. 
In Mexico, Banco de México cut its policy rate to 7.25%, in line with expectations. September remittances fell 2.7% YoY, though they remain above $5 billion. 

“The investor’s chief problem — and even his worst enemy — is likely to be himself.” — Benjamin Graham 

Important Events: 

  • U.S. October inflation data will be released — November 13 
  • U.S. Producer Price Index (PPI) will be published — November 14 

Monitor

Global Financial Outlook: Fed Cuts Rates and U.S. Extends Tariff Truce with China 

The week was marked by mixed signals in global markets following a series of key events. These included the Federal Reserve’s (Fed) second consecutive policy rate cut, the extension of the tariff truce between the United States and China, the stagnation of the German economy, and the improvement in China’s industrial profits. These developments underscore the complexity of the global economic and trade environment. 

United States: 

  • The Federal Reserve cut the policy rate to a range of 3.75% – 4.00%. 
  • Trump and Xi agreed to extend the tariff truce for one more year. 
  • Consumer confidence fell to its lowest level in six months. 
  • Earnings season continues to show strength, with S&P 500 earnings growing about 10% this quarter. 

Europe

  • The European Central Bank (ECB) kept its key rate at 2%. 
  • Germany’s economy stagnated due to weaker exports and ongoing global trade pressures, despite a slight improvement in business sentiment. 

Japan

  • The government highlighted a moderate recovery supported primarily by capital spending. 
  • Caution persists due to risks linked to U.S. trade policy. 

China:

  • Industrial profits rose 21.6% YoY in September, the fastest pace since November 2023. This reflects better capacity utilization. 

Brazil

  • The U.S. Senate approved a bill to revoke tariffs on Brazil by lifting the national emergency declaration issued in July. 

Mexico:

  • Gross Domestic Product (GDP) contracted 0.3%YoY in 3Q25. 
  • According to President Sheinbaum, the United States extended the negotiation period to avoid the implementation of a 30% tariff. 

“Compound interest is the eighth wonder of the world. He who understands it, earns it; he who doesn’t, pays it.” – Albert Einstein 

Key Upcoming Events 

  • U.S.: ISM Manufacturing – Nov 3. 
  • U.S.: ISM Services & employment-related data (tentative) – Nov 5-7. 

Monitor

Fed cuts again but remains cautious

The Federal Reserve delivered its second rate cut of the year, lowering the policy rate by 25 bps to a range of 3.75%–4%. It announced that it will halt its balance sheet reduction in December. 

The Fed acknowledged moderate growth but warned of rising labor market risks.  The vote was 10–2, reflecting divided positions. 


Powell: another cut in December is not guaranteed. 

Key Data: 

  • Second rate cut of 2025 
  • Rate range: 3.75%–4% 
  • Vote: 10–2 
  • Balance sheet runoff to end in December 
  • Labor market risks on the rise 


The market continues to expect a possible third rate cut in December, though signals remain mixed. 
The Fed remains cautious and data-dependent, with employment as a key variable guiding the rate path. 

Global Outlook: Mixed Signals and Market Caution

Week: October 13–17 

Markets showed a mix of recovery signs and new challenges, driven by trade tensions, monetary policy decisions, and corporate earnings. 

United States 

  • Tensions with China escalated following new statements from President Trump. 
  • Chair Powell suggested the end of the tightening cycle, opening the door to potential rate cuts. 
  • Banks reported solid earnings, though volatility persists among regional banks. 

Europe 

  • German investor confidence rose less than expected. 
  • The U.K. economy grew 0.1% in August, but with downward revisions to prior data. 
  • The IMF urged the Bank of England to remain cautious, as inflation is expected to stay the highest in the G7. 

Asia 

  • In China, exports rose 8.3% year-over-year in September, the fastest pace in six months. 
  • Inflation fell again (-0.3%), reflecting weak domestic demand and ongoing trade tensions. 
  • Producer prices dropped 2.3% annually. 

Latin America 

  • In Brazil, the economy expanded 0.4% in August, below expectations. Analysts expect a deeper slowdown as monetary policy remains tight. The Central Bank maintained its benchmark rate at 15%. 
  • In Mexico, the IMF projects a fiscal deficit of 3.9% of GDP for 2025 — the highest since 2000. The government is assessing potential tariff adjustments for 2026, depending on U.S.–China trade developments. 

“Risk comes from not knowing what you are doing.” — Warren Buffett 

Key Upcoming Events: 

  • China: GDP, industrial production, and retail sales data — October 20 
  • United States: Consumer prices and new home sales — October 24 

Monitor: 

U.S. Government Shutdown: Political Uncertainty, Market Resilience 

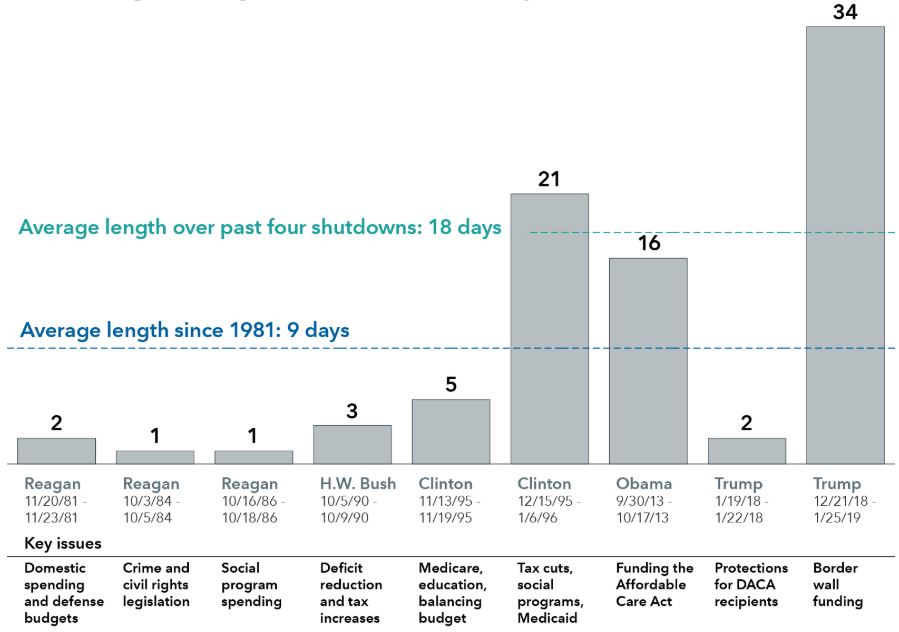
The U.S. government shutdown is once again testing market patience amid stalled negotiations and disagreements over public spending. Unlike previous shutdowns, this time there is talk of permanent layoffs instead of temporary furloughs, which could have a stronger impact on employment and domestic consumption. However, historical evidence suggests that such events tend to have a limited effect on financial asset performance over the medium and long term. The main market drivers remain fundamentals: inflation, interest rates, earnings, and employment. 

Key Data: 

  • Average government shutdown duration: 9 days 
  • Longest shutdown: 34 days (2018–2019) 
  • Potential permanent layoffs could have longer-lasting effects 

The key is to stay focused, avoid hasty decisions, and rely on diversification as protection against political noise. 

Source: Capital Group  

Cierre del gobierno en EE. UU.: incertidumbre política, resiliencia de mercado 

El cierre del gobierno en Estados Unidos vuelve a poner a prueba la paciencia de los mercados, en medio de negociaciones estancadas y desacuerdos sobre gasto público. A diferencia de cierres anteriores, esta vez se contempla la posibilidad de despidos permanentes en lugar de suspensiones temporales, lo que podría impactar más al empleo y al consumo interno. Sin embargo, la experiencia histórica sugiere que estos eventos suelen tener un impacto limitado en el desempeño de los activos financieros a mediano y largo plazo. Los factores fundamentales siguen siendo los principales motores del mercado: inflación, tasas de interés, utilidades y empleo. 

Datos clave: 

  • Duración promedio de cierres de gobierno: 9 días 
  • Cierre más largo: 34 días (2018–2019) 
  • Posibles despidos permanentes podrían generar efectos más duraderos 

La clave está en mantener el enfoque, evitar decisiones precipitadas y apostar por la diversificación como protección frente al ruido político. 

Fuente: Capital Group  

Week of Uncertainty in the U.S. and Surprises in Asia 

Markets opened October with mixed signals. Attention focused on the ongoing U.S. government shutdown, revised growth forecasts in China and Mexico, and stronger trade performance in Brazil. In Asia, Japan saw a historic political shift with the election of Sanae Takaichi as leader of the ruling party, while Europe faced renewed political instability. 

United States: 

  • The government shutdown remains unresolved. 
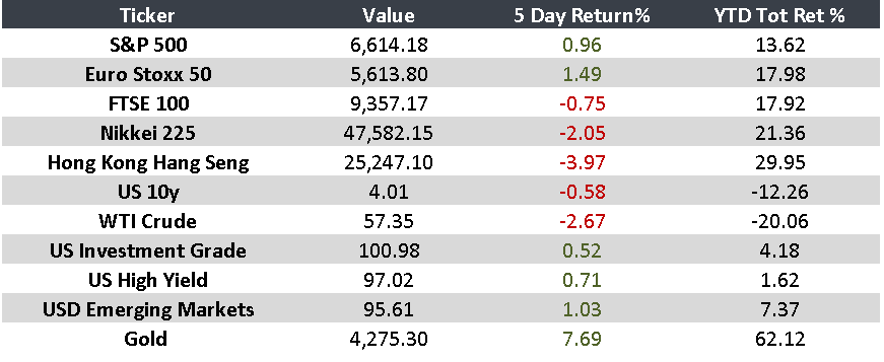
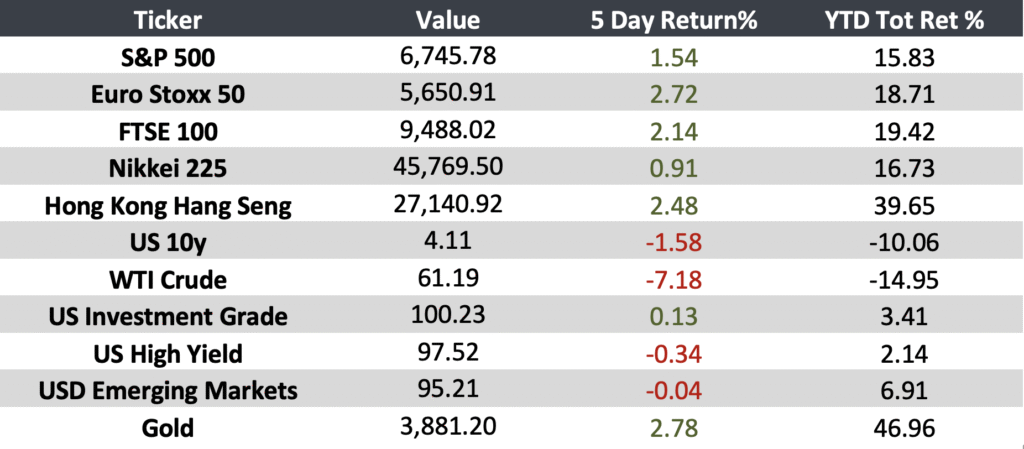
  • Gold surpassed $4,000 amid political and fiscal uncertainty. 
  • The Fed signaled openness to rate cuts, though doubts persist about their extent. 

Europe: 

  • France faced an unexpected resignation from its prime minister. 
  • In Germany, exports and factory orders fell. 
  • The government raised its 2024 growth forecast to 0.2%. 

Asia: 

  • In Japan, Sanae Takaichi was elected leader of the ruling party, positioning her to become the country’s first female prime minister. 
  • In China, despite the holiday break, the World Bank raised its growth forecast to 4.8%, and the government tightened export controls on rare earth minerals. 

Latin America: 

  • In Brazil, beef exports to China rose 38.3% year-over-year in September, setting a new trade record. 
  • In Mexico, inflation rose to 3.76% in September. The World Bank revised its 2025 growth forecast upward to 0.5% and anticipates 1.4% for 2026. 

“The four most dangerous words in investing are: ‘This time it’s different.’” — John Templeton 

Key Upcoming Events: 

  • China: Export and inflation data — October 12–15 
  • United States: Inflation report — October 15 

Monitor

Key Market Moves | Weekly Summary

General Summary: Markets faced mixed signals last week, balancing political uncertainty in the U.S., inflationary pressures in Europe, and weakness in Asia. Meanwhile, Latin America showed resilience in public finances and corporate outlooks.

United States

  • The government remains shut down, the first in nearly seven years, delaying official labor data. Still, markets closed higher on optimism for a short shutdown and strong tech sector performance.
  • ADP reported a reduction of 32,000 jobs in September, the largest decline since March 2023.
  • Consumer confidence fell more than expected, while President Trump announced an agreement with Pfizer to voluntarily lower drug prices.

Europe

  • UK GDP slowed to 0.3% in Q2 (vs. 0.7% in Q1), in line with expectations.
  • German inflation accelerated to 2.4% YoY, the highest since February, while unemployment rose by 14,000 to 2.98M.
  • The European Union plans to double steel tariffs to 50%, aligning with the U.S. against Chinese overcapacity.

Asia

  • Japan: Industrial production fell 1.2% MoM, while retail sales dropped 1.1%, the first contraction in over three years.
  • China: Manufacturing activity contracted for the sixth consecutive month, awaiting new stimulus measures and clearer U.S. trade relations.

Latin America

  • Brazil: Public finances exceeded expectations; debt held at 77.5% of GDP, and the primary deficit was ~BRL 17B (~USD 3B), lower than projected.
  • Mexico: Fitch plans to raise Pemex’s rating from BB to BB+ after a USD 10B bond buyback, highlighting closer ties with the sovereign. The government emphasized economic resilience and projects 2.3% average growth in 2026.

“In investing, what is comfortable is rarely profitable.” — Robert Arnott

Important Events:

  • U.S.: Fed officials’ speeches — October 7–10
  • U.S.: Fed minutes — October 8

Monitor

S&P 500 Earnings Outlook — 3Q 2025

The S&P 500 shows resilience heading into 3Q 2025, with reasonable earnings growth expectations despite a challenging macroeconomic backdrop. Below are the main takeaways for the upcoming earnings season: 

Earnings Growth 

  • Earnings (EPS) are projected to grow 7.9% YoY in 3Q 2025. If confirmed, this would mark the ninth consecutive quarter of growth for the S&P 500. As of June 30, the growth estimate stood at 7.3%. 
  • Six sectors have seen upward revisions to estimates, contributing to stronger earnings expectations. 

Sector Growth 

  • Eight of the eleven sectors are projected to post annual growth, led by Information Technology, Utilities, Materials, and Financials. 
  • Three sectors are expected to report annual declines, mainly Energy and Consumer Staples. 

Revenues 

  • Revenues are expected to grow 6.3% YoY, compared to the 4.8% projection as of June 30. 
  • If confirmed: 
    o This would be the second-largest revenue growth since 3Q 2022 (11.0%), only behind the previous quarter. 
    o It would mark the 20th consecutive quarter of revenue growth for the index. 

Valuation 

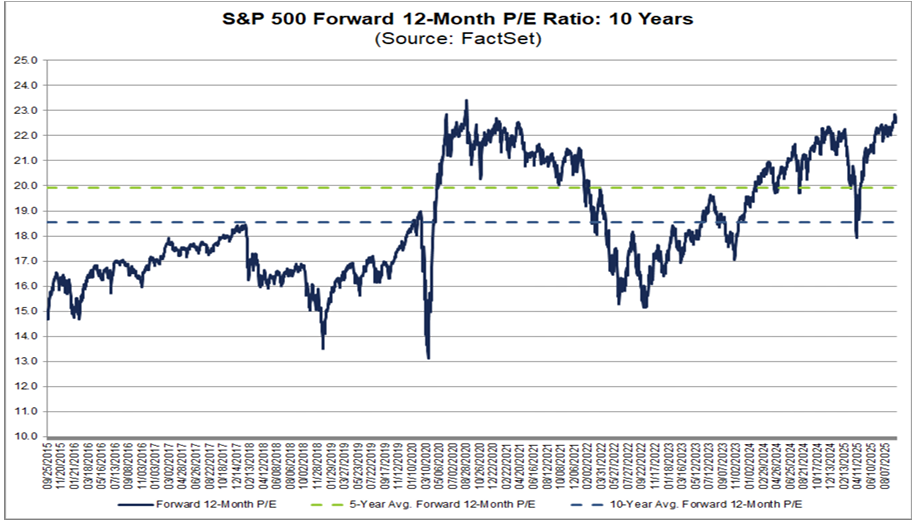
  • The S&P 500 forward 12-month P/E multiple stands at ~22.5x, above the 5-year average (19.9x) and the 10-year average (18.6x). 
  • This suggests that while earnings growth continues, valuations remain tight with much optimism already priced in. 

Key data points for the quarter: 
☑ EPS growth estimate +7.9% YoY in 3Q 2025 (vs. 7.3% as of June 30) 
☑ Six sectors with upward revisions 
☑ 8 of 11 sectors projected to grow 
☑ Revenues +6.3% YoY (vs. 4.8% as of June 30) 
☑ 20th consecutive quarter of revenue growth 
☑ Forward 12-month P/E ~22.5x (vs. 19.9x 5-year avg. and 18.6x 10-year avg.) 

Corporate performance remains resilient, with earnings growth expectations of 10.8% in 2025 and 13.8% in 2026 — outlooks that investors will closely monitor in a context of valuations above historical averages. 

Source: FactSet 

Ponte en contacto con nosotros

Receive the best financial market news

Cookie Policy

We use our own and third party cookies to improve our services and show you advertising related to your preferences, by analyzing your browsing habits. By continuing, you confirm that you have read and accept this policy.