Jacobo Taurel

Private debt under pressure in a more challenging environment 

Private debt, though a core component of institutional portfolios for several years, is currently experiencing strong growth. However, a challenging macroeconomic backdrop and multiple structural forces are reshaping the dynamics of private financing.

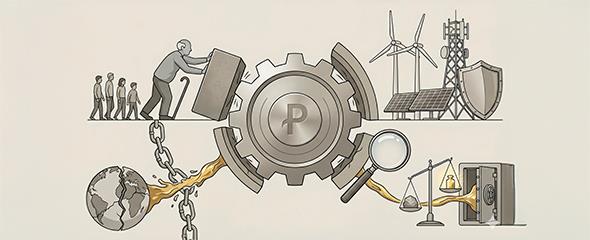
Aging populations and declining birth rates are reducing demographic growth, further increasing the cost of capital. At the same time, the energy transition, national defense, digital infrastructure, and other strategic priorities require trillions of dollars in annual investment, creating fierce competition for scarce capital.

Additionally, regulatory pressure, deglobalization, and macroeconomic volatility are increasing liquidity risk across certain segments of private debt. While the asset class remains attractive due to its ability to generate above-market returns, a more rigorous assessment of credit risk has become essential.

Key Data: 

  • Aging populations increase the cost of capital 
  • Energy transition and infrastructure demand trillions annually 
  • Regulatory pressure and deglobalization heighten liquidity risk 
  • The era of cheap capital is over 

Conditions have changed. Selectivity and credit quality are now more important than ever. Although private debt offers attractive returns, the current environment demands more rigorous analysis. A disciplined approach to credit quality and liquidity risk assessment enables capturing opportunities without compromising portfolio soundness.

Source: Activest/Axxets Internal Analysis 
Fed splits opinions and key data ahead 

Markets reacted to the Federal Reserve’s latest rate cut amid a set of mixed signals on inflation, production, and employment across major economies. The week was shaped by U.S. labor data, an industrial rebound in Europe, and contrasting dynamics in Asia and Latin America, reinforcing a cautious outlook for monetary policy heading into 2026. 

United States 

  • The Fed cut rates to a range of 3.50%–3.75%, with three dissenting votes. 
  • Policymakers signaled only one additional adjustment in 2026. 
  • Labor cost growth moderated. 
  • Job openings remained stable, pointing to easing wage pressures. 

Europe (Germany) 

  • Industrial production rose 1.8% in October, the strongest increase since March. 
  • Growth was driven by machinery and electronics. 
  • Exports increased 0.1%, supported by intra-EU trade, despite weaker shipments to the U.S. and China. 

Japan 

  • Producer prices rose 2.7% year over year in November, unchanged from the previous month. 
  • The strongest increases were seen in nonferrous metals and food & beverages. 

China 

  • Annual inflation rebounded to 0.7%, the highest level since February. 
  • Food prices rose for the first time in ten months. 
  • Producer prices fell 2.2%, extending a 38-month contraction amid weak domestic demand. 

Brazil 

  • Annual inflation declined to 4.46%, its lowest level since September 2024. 
  • The Central Bank held its policy rate at 15.00%. 
  • Authorities signaled a prolonged pause to ensure convergence toward the inflation target. 

Mexico 

  • Inflation rose to 3.80% year over year, the highest reading since June. 
  • Auto production fell 8.4% year over year in November. 
  • Year-to-date, production is down 1.5%. 

“The single greatest edge an investor can have is a long-term orientation.” 
— Seth Klarman 

Key Upcoming Events 

  • United States: Nonfarm payrolls report — December 16 
  • United States: November inflation report — December 18 

Monitor 

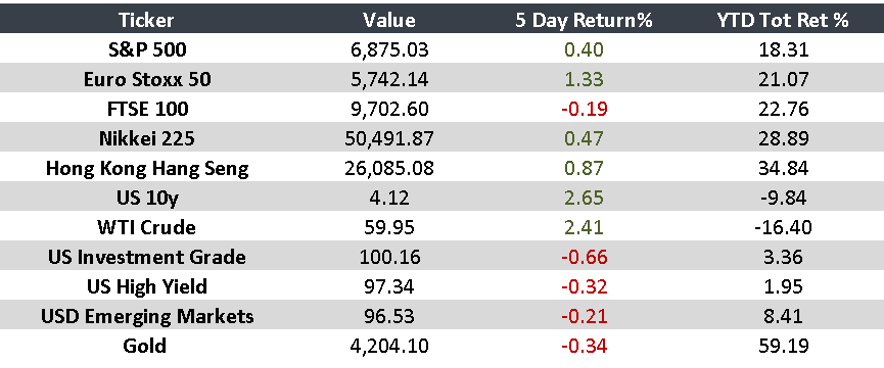
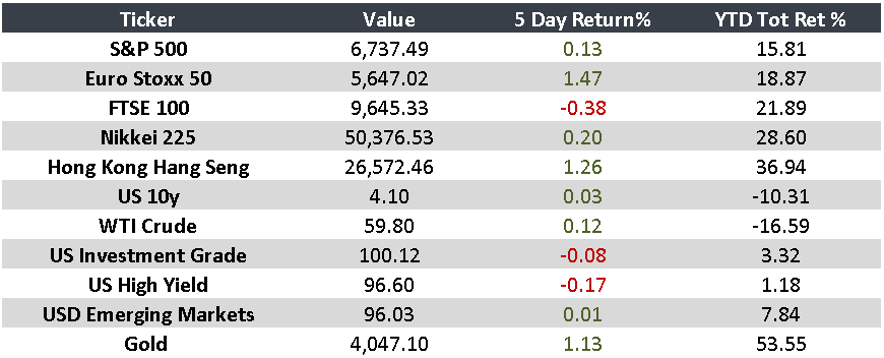
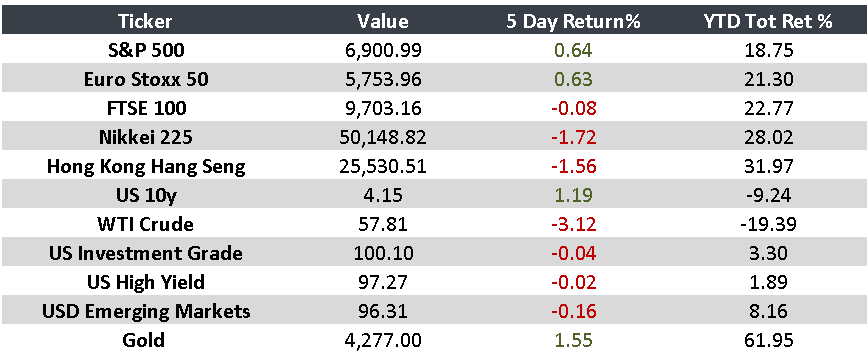
Returns as of market close on December 11. 

Fed: Mixed Signals After the Latest Rate Cut

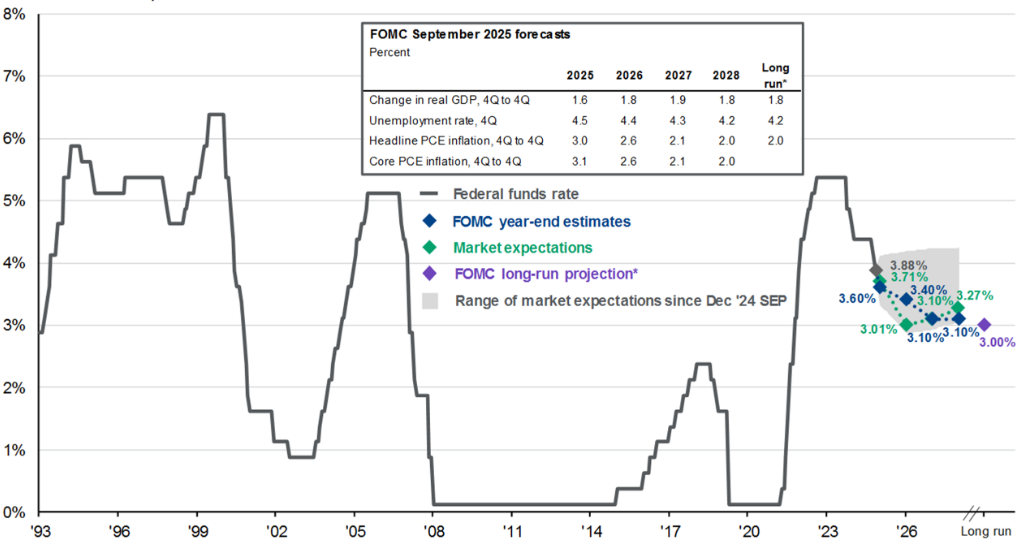
The Federal Reserve delivered its third consecutive rate cut, lowering the federal funds rate to a range of 3.50%–3.75%. While the move was widely anticipated, the accompanying statement revealed rising uncertainty about the policy path ahead. The committee showed an unusual split between members focused on labor-market weakness and those still concerned about persistent inflation pressures.

The updated dot plot, which reflects policymakers’ rate expectations, pointed to just one additional cut in 2026 and another in 2027. Although the projected path remained unchanged, it underscored diverging views within the committee regarding the appropriate level of interest rates over the medium term.

The latest rate cut confirms that the Fed maintains an accommodative bias, but the internal divisions suggest that the pace of future adjustments is likely to slow. In this environment, markets are expected to remain highly sensitive to incoming employment, inflation, and monetary policy expectation data throughout 2026.

Source: JP Morgan

Mixed signals: weak manufacturing, moderating labor data, and rising expectations of rate cuts 

Markets ended the week focused on the persistent weakness in global manufacturing activity and the continued loss of momentum in the U.S. labor market. In this environment, expectations for a potential interest rate cut before year-end strengthened. Europe and Asia showed mixed signals, while Latin America posted contrasting results across growth and income indicators. 

United States: 

  • Manufacturing contracted for the ninth consecutive month, while the services sector recorded its strongest expansion in nine months. 
  • Private employers cut 32,000 jobs, reinforcing expectations of a December rate cut, now priced with an 87% probability. 

Europe: 

  • The Bank of England reduced capital requirements for the first time since 2008 in an effort to stimulate lending. 
  • Eurozone inflation reached 2.2% year over year, with services remaining the main driver. 

Japan: 

  • The services sector maintained a solid pace of expansion in November, supported by rising new orders and improved business confidence. 

China: 

  • Manufacturing contracted for the eighth straight month, while services grew at their slowest pace in five months. 
  • Analysts expect additional expansionary measures to help sustain a growth target near 5% in 2026. 

Brazil: 

  • GDP grew 1.8% year over year in 3Q25, its weakest reading since 2022. 
  • Agriculture and industry remained the main contributors despite the slowdown. 

Mexico: 

  • Remittances fell 1.7% year over year in October, marking the smallest decline since April. 
  • The minimum wage will increase 13% in 2026 to 315.04 pesos per day, a cumulative rise of 150% since 2018. 

“Risk comes from not knowing what you’re doing.” — Warren Buffett 

Key Upcoming Events: 

  • United States: Employment data release — Dec 9 
  • United States: Federal Reserve monetary policy announcement — Dec 10 

Monitor

Is the Santa Claus Rally real?

A seasonal rally or just a myth? 

The “Santa Claus Rally” describes a historical pattern: markets tend to rise during the final days of December and early January. We analyze its consistency and what to expect heading into 2025. 

In the financial world, the “Santa Claus Rally” describes a historical pattern: markets tend to rise during the last five trading days of December and the first two of January. According to the Stock Trader’s Almanac, this phenomenon has occurred approximately 78%–80% of the time since 1972, with an average return of 1.3% to 1.4% for the S&P 500. 

Possible reasons range from lower trading volume as many institutional investors take time off, to a more optimistic emotional tone driven by the holidays, year-end bonuses, and portfolio adjustments like rebalancing or tax-loss harvesting. 

However, it doesn’t always happen. Over the past decade, the effect has been weaker, with average returns around 0.38%. Factors like inflation, elevated rates, geopolitical tensions, or economic surprises have completely negated this seasonal boost. 

Key Takeaways: 
✓ While the Santa Claus Rally has shown historical consistency, factors like elevated rates, inflation, and volatility limit its reliability as a strategy. If it happens, view it as an extra boost—not a basis for decision-making. 
 
✓ The Santa Claus Rally refers to the market uptick during the last five trading days of December and the first two trading days of January. 

Rate Cuts: How Close Are We? 

In a holiday-shortened week, U.S. labor data and inflation trends in Latin America took center stage. Expectations around the Federal Reserve’s next move are once again driving market sentiment. 

United States: 

  • Consumer confidence fell to its lowest level since April, and layoffs continued to rise, pushing the probability of a December rate cut to 84%, up from 39% the previous week. 

Europe: 

  • Business confidence in Germany unexpectedly weakened. In the United Kingdom, the new fiscal budget includes tax increases amid an environment of sluggish economic growth. 

Japan: 

  • Prime Minister Sanae Takaichi heightened diplomatic tensions with China after stating that Japan could intervene if Beijing acts against Taiwan, adding uncertainty to the regional outlook. 

China: 

  • Industrial profits fell 5.5% in October, while the government adopted a firmer stance regarding Taiwan, amplifying geopolitical risks across Asia. 

Brazil: 

  • Annual inflation slowed to 4.50% in November, returning to the central bank’s target range for the first time since January—an outcome welcomed by markets. 

Mexico: 

  • Inflation rose to 3.61% in the first half of November. Banxico revised its 2025 growth forecast down from 0.6% to 0.3%, while keeping its 2026 estimate unchanged at 1.1%. 

“The thesis underlying everything, whether you’re an actively managed fund or a passive fund, is that the U.S. will be OK. If you don’t believe that, you shouldn’t be in the stock market.” — Peter Lynch 

Key Upcoming Events: 

  • United States: Second estimate of Q3 2025 GDP and ISM Manufacturing — December 2 
  • United States: ISM Services Index — December 3 

Monitor

Stablecoins: Innovation or silent threat to money?

Stablecoins pose a structural challenge to global monetary policy, potentially driving persistent inflation above central bank targets. Central banks don’t regulate or control stablecoin issuance, limiting their ability to adjust money supply across economic cycles. While currently backed 1:1 by fiat, a shift to fractional reserves could amplify inflation. 24/7 DeFi transactions accelerate monetary velocity, amplifying liquidity and inflationary pressures. Stablecoin-backed DeFi lending creates excessive leverage, risking bubbles that affect both crypto ecosystems and real-world assets. 

Key data: 

  • Stablecoins monetize otherwise immobilized assets (dollars, Treasuries) 
  • 24/7 transactions outside central bank control 
  • Long-term rates could reach ~3.5% 
  • 150 basis points above the past decade 

Stablecoins aren’t just redefining global liquidity; they’re silently expanding the foundation for structural inflation. Combined with demographics, energy transition, and deglobalization, they drive structural inflation, affecting monetary policy and asset class returns. 

Jobs, the Fed, and Growth: A Week of Mixed Signals 

The U.S. labor market returned to the spotlight this week, while Europe maintained a stable tone and Japan showed signs of cooling. In Mexico, foreign direct investment continued to strengthen. Here are the key topics to watch. 

United States: 

• The economy added 119,000 jobs in September, above expectations, although the unemployment rate rose to 4.4%. 
• The Fed remains divided, and the probability of a December rate cut currently stands at 40%. 

Europe: 

• Inflation remains stable near 2%, and the ECB is expected to keep rates unchanged at least through the end of 2026. 
• In the UK, inflation fell to 3.6%, potentially opening the door for a rate cut by the Bank of England in December. 

Japan: 

• GDP fell 1.8% annualized in the third quarter, with a quarterly contraction of 0.4%. 
• Exports were the main drag, reflecting a weaker external backdrop. 

China: 

• For the sixth consecutive month, the central bank kept its benchmark lending rates unchanged. 
• The decision was in line with expectations as the economy seeks stability amid domestic challenges. 

Mexico: 

• FDI grew 14.5% year-over-year from January to September, surpassing $40 billion. 
• Economic activity showed no change in October, both month-over-month and compared with the same month in 2024. 

“Be fearful when others are greedy and greedy only when others are fearful.” — Warren Buffett 

Key Upcoming Events: 

• U.S.: Beige Book release — 11/26 
• U.S.: Thanksgiving Day (market holiday) — 11/27 

Monitor

Stablecoins: The Hidden Key Piece Driving Interest Rates and Global Liquidity

Stablecoins are no longer a theoretical exercise but have become part of the global financial market. With a capitalization exceeding $200 billion and high growth, their impact on the global economy is undeniable. Despite this, they remain excluded from monetary indicators like the M2 Money Supply. This omission is, in our opinion, a technical legacy that must soon be corrected. 

Stablecoins meet all M2 criteria: near-immediate liquidity, backing by fiat money like USD, and transactional use. They function as a new layer of private global money, operating in parallel to the traditional system. These assets monetize immobilized assets (like Treasury bonds), increasing the effective monetary base without central bank intervention. 

Key Data Points: 

  • Capitalization exceeds $200 billion. 
  • Meet all M2 criteria (liquidity, fiat backing, transactional use). 
  • They monetize Treasury bonds, increasing the effective monetary base. 
  • Their exclusion may imply recognizing higher inflation. 

Institutional resistance to including them in official statistics is not due to a lack of merit, but structural inertia and a possible political dilemma. The expansion of stablecoins represents an evolution in monetary architecture. Ignoring them is a risk; incorporating them into M2 is a necessity. 

Global Outlook: Mixed Signals in Inflation and Employment Amid Divided Fed Stances 

Markets moved through a week of soft economic activity in the U.S. and mixed signals across global regions. Key developments included monetary policy adjustments, moderate growth figures, and relevant updates on inflation and employment. This backdrop underscores the importance of analyzing structural trends, not just short-term market moves. 

  • United States: The agreement to fund the government through January ended the longest shutdown on record, while the Fed showed mixed views on future rate cuts. The technology sector remained volatile amid valuation concerns. 

  • Europe: The U.K. labor market weakened, with unemployment rising to 5.0%—its highest level since 2021. 3Q25 growth slowed, reinforcing expectations for a Bank of England rate cut. The eurozone economy continued to expand at a modest pace in the third quarter. 

  • Japan: The Bank of Japan reiterated that it aims for moderate inflation supported by wage growth and improving economic conditions, in line with the government’s broader growth strategy. 

  • China: Producer prices fell 2.1% year over year—less than expected—while consumer inflation rose 0.2%, reversing two months of declines. Industrial production and retail sales also delivered weak readings. 

  • Brazil: Monthly inflation rose 0.09%, helped by lower electricity tariffs, while the annual figure dropped to 4.68%. The central bank is preparing additional regulations to address the increase in cyberattacks. 

  • Mexico: Industrial activity fell 3.3% in September, marking seven consecutive months of contraction. Banxico expects inflation to converge to 3% by 3Q26 and anticipates only limited impact from new taxes. 

“We don’t prognosticate macroeconomic factors; we’re looking at our companies from a bottom-up perspective on their long-run prospects of returning.” – Mellody Hobson 

Key Upcoming Events:  

  • United States: Industrial production – 11/18. 
  • United States: Federal Reserve minutes – 11/19. 

Monitor

Ponte en contacto con nosotros

Receive the best financial market news

Cookie Policy

We use our own and third party cookies to improve our services and show you advertising related to your preferences, by analyzing your browsing habits. By continuing, you confirm that you have read and accept this policy.