Weekly Global Outlook
Week of August 31 to September 4
Resilient employment, persistent inflation, and new signals on the path of interest rates.
The global economy continued to show resilience, although price pressures remain. U.S. employment surprised to the upside, while Europe faces higher inflation and Asia shows more favorable economic activity.
United States
- The economy added 162,000 jobs in August, beating expectations, while the 10-year Treasury yield reached 4.818%. Markets raised the probability of a Fed rate hike to 58%.
Europe
- Inflation rose to 3.3% year over year in August, driven by energy prices and reinforcing expectations of an ECB rate hike. Manufacturing PMI also improved, supported by Germany.
Japan
- Retail sales rose 4% year over year in July, beating expectations. Manufacturing PMI remained in expansion in August, supported by exports and employment, although cost pressures persisted.
China
- Manufacturing and services PMIs improved in August. Manufacturing remained in contraction, although output and new orders rebounded, while services benefited from stronger domestic demand.
Argentina
- Agricultural exports rose 51% year over year in August. The sector generated approximately USD 2.75 billion during the month, strengthening a key source of foreign currency for the economy.
Brazil
- GDP grew 0.5% quarter over quarter in Q2, supported by investment and government spending. Industrial production rose 0.2% in July, while household consumption remained pressured by inflation.
Mexico
- Fixed investment rose 7.7% year over year in June, supported by public construction. In August, auto sales increased 4.7% annually and consumer confidence reached a one-year high.
“Investing is the intersection of economics and psychology.”
— Phil Town
Upcoming Events
- In the United States, August PPI data will be released — 09/10
- In the United States, August inflation data will be released — 09/11
Market Monitor
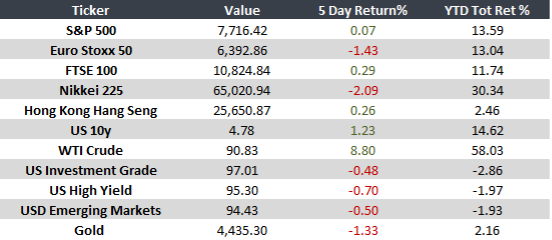
Indicative prices as of 10:00 AM EST

