Weekly Global Outlook
Week of September 7–11
Persistent inflation, higher interest rates, and mixed signals for global growth.
Inflation returned to the forefront of market attention. The Fed and ECB face greater pressure on interest rates, while Asia shows mixed signals and Latin America continues to see a gradual easing in price pressures.
- United States: Annual inflation stood at 3.4% in August, while PPI reached 5.4%. Markets raised the probability of a Fed rate hike in September to 87% amid greater energy-related price pressures.
- Europe: The ECB raised its policy rate to 2.50% amid 3.3% inflation and heightened energy risks. In Germany, inflation rose to 2.9%, while exports declined in July.
- Japan: The economy grew at a 1.4% annualized rate in Q2 2026, supported by government spending and exports. Producer prices rose 7.6% year over year, reflecting persistent energy and raw material cost pressures.
- China: Exports rose 25% year over year in August, supported by technology and AI-related demand. Consumer inflation increased to 0.8%, while producer prices rose 3.8% amid higher energy costs.
- Argentina: Annual inflation eased to 33.7% in August, with prices rising 1.7% month over month, down from 2.1% in July. Year-to-date inflation reached 21.3%.
- Brazil: Annual inflation eased to 4.22% in August, while consumer prices fell 0.32% month over month, supported by softer price pressures in transportation and housing.
- Mexico: Inflation stood at 3.26% year over year in August. The Ministry of Finance projects a fiscal deficit of 3.9% of GDP and growth of 1.5%–2.5% in 2027, while auto production fell 1.4% year over year.
“Time is your friend, impulse is your enemy.”
— John Bogle
Upcoming Events
- In the United States, retail sales data will be released — 09/16
- In the United States, the FED’s monetary policy decision will be announced — 09/16
Market Monitor
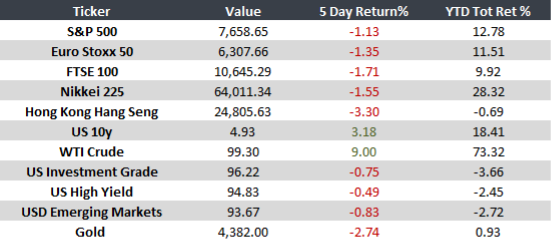
Indicative prices as of 10:00 AM EST

