Weekly Report
Every Friday the Activest investment team reads the week just closed: what moved, what it means for portfolios, and what sits on next week’s calendar.
-
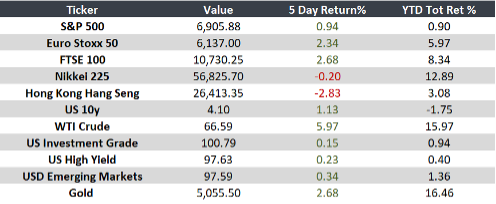
Moderate Growth and Mixed Signals
Week of February 16–20 The week brought signs of slowing growth in the U.S., persistent inflation pressures in Europe, and ongoing adjustments…
-
Weekly global macro outlook
February 9–13 The global economy continues to show moderate growth, with inflation easing in developed markets while emerging markets face more persistent…
-
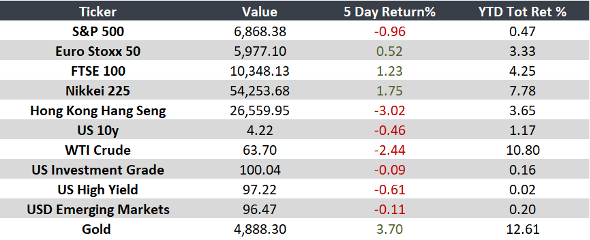
Mixed signals in employment, inflation, and global activity
Week of February 2 – 6 The week delivered mixed signals: strong corporate earnings resilience in the U.S., moderating inflation in Europe,…
-
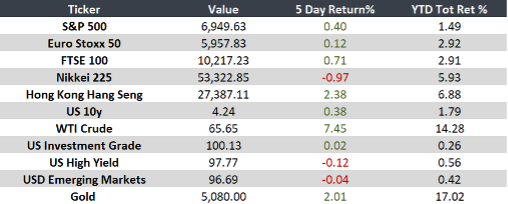
Global outlook: inflation, growth, and trade
Week of January 26 to 30 Global markets reflect a balance between solid growth in developed economies, persistent inflationary pressures in certain sectors, and ongoing monetary policy…
-
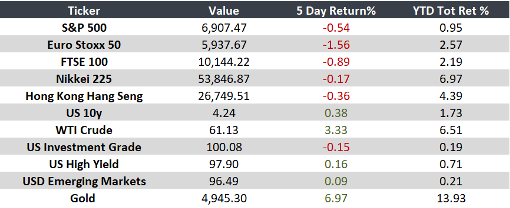
Global outlook: growth and inflation in focus
Week of January 19–23 Global markets reflect a balance between resilient growth, easing inflation in some regions, and persistent pressures in others, shaping monetary policy expectations and economic activity in 2025. United States Q3 GDP was revised up to a 4.4% annualized rate, driven by exports, business investment, and strong consumer spending. The Federal Reserve is expected to keep rates at 3.50%–3.75% this quarter, reflecting a cautious stance amid mixed economic data. Europe Eurozone inflation closed 2025 at 1.9%, below the European Central Bank’s 2% target. Germany’s economic confidence improved after several difficult quarters, while the United Kingdom continues to face persistent inflation pressures that complicate monetary policy decisions. Japan Inflation eased to 2.1% year over year in December. Lower energy prices offset underlying pressures, although core inflation remains above the Bank of Japan’s target, maintaining uncertainty about future monetary adjustments. China GDP grew 4.5% in the fourth quarter, weighed down significantly by the real estate…
-
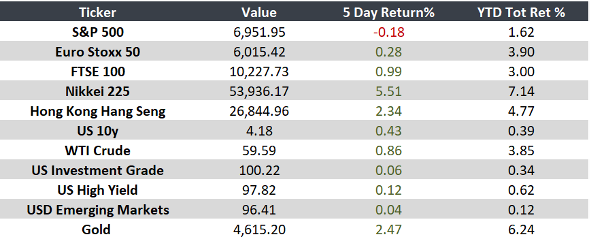
Mixed outlook between inflation and growth
Week of January 12–16 Key data on inflation, consumption, and growth shape the start of 2026 This week, markets reacted to mixed signals: stable U.S. inflation, positive surprises in retail sales, and uneven growth across Europe. Meanwhile, China strengthened its global trade presence, and Argentina closed the year with its lowest inflation in eight years. United States Headline inflation held at 2.7% and core inflation at 2.6%. PPI…
-
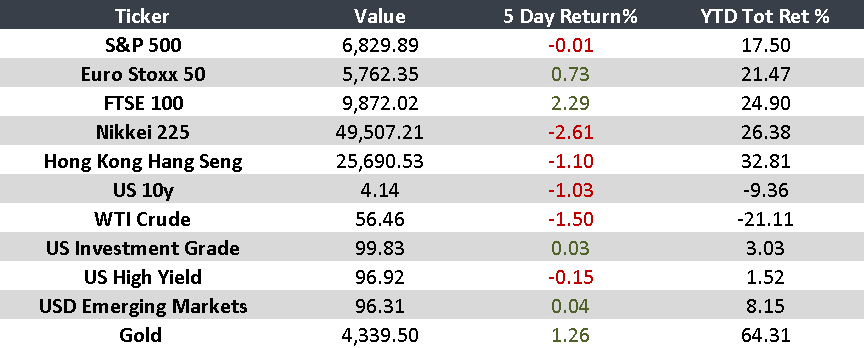
Global Economic Outlook: Mixed Signals
Week December 15–19 In a relatively calm week, employment and consumption indicators provided key signals across major economies. Central bank decisions continue to reflect…
-
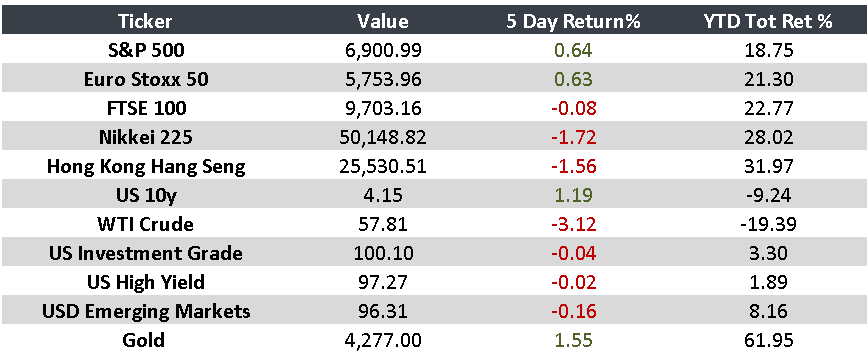
Fed splits opinions and key data ahead
Week December 8–12 Markets reacted to the Federal Reserve’s latest rate cut amid a set of mixed signals on inflation, production, and employment…
-
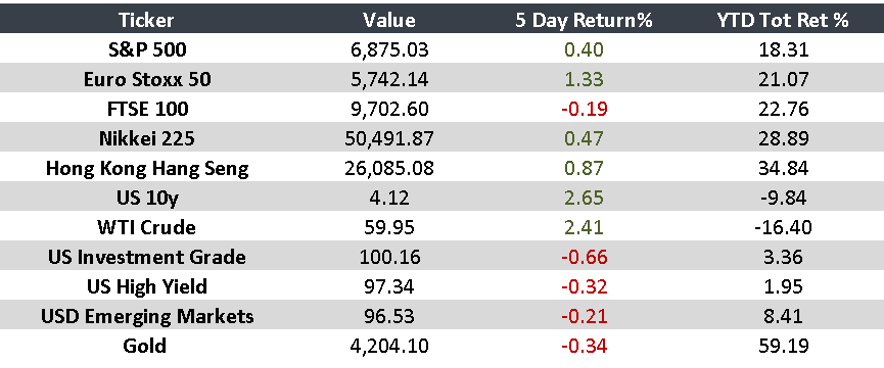
Mixed signals: weak manufacturing, moderating labor data, and rising expectations of rate cuts
Week: December 1–5 Markets ended the week focused on the persistent weakness in global manufacturing activity and the continued loss of momentum in…
-
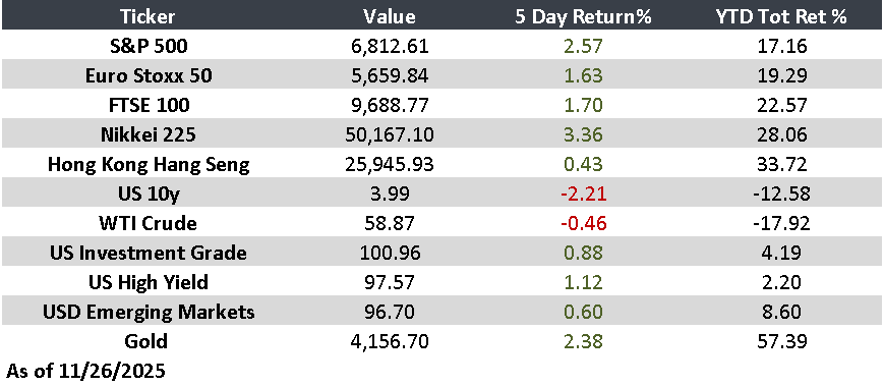
Rate Cuts: How Close Are We?
November 24–26 In a holiday-shortened week, U.S. labor data and inflation trends in Latin America took center stage. Expectations around the Federal…
-
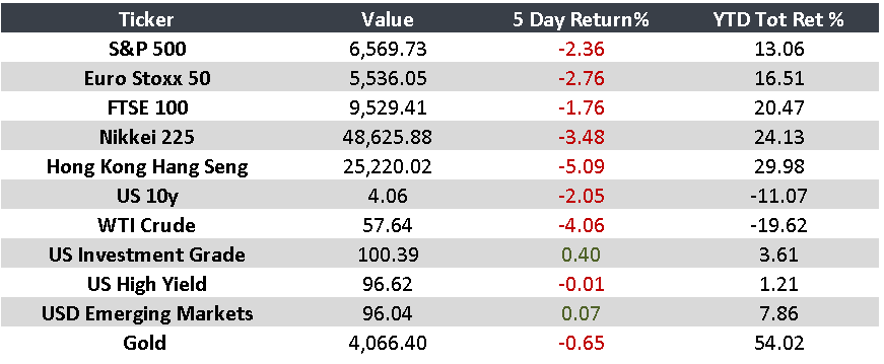
Jobs, the Fed, and Growth: A Week of Mixed Signals
November 17–21 The U.S. labor market returned to the spotlight this week, while Europe maintained a stable tone and Japan showed signs…
-
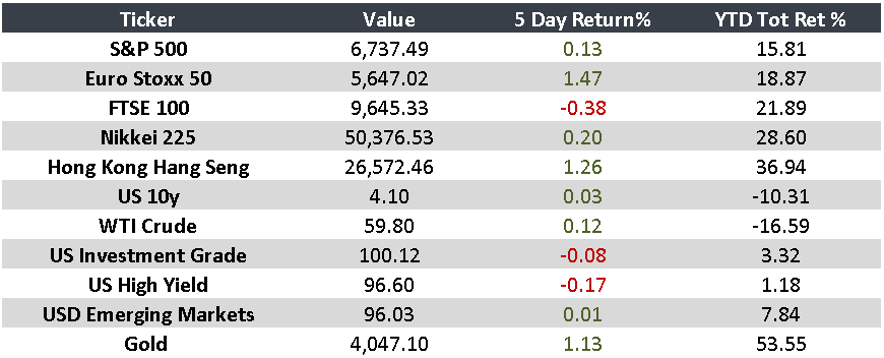
Global Outlook: Mixed Signals in Inflation and Employment Amid Divided Fed Stances
Week: Week of November 11-15 Markets moved through a week of soft economic activity in the U.S. and mixed signals across global…